Challenger Brand Study 2027, Part I: A Look Back to Move Forward

Challenger Brand Study 2027, Part I: A Look Back to Move Forward
A magnifying glass over a blurred city at night, the cover of Challenger Brand Study 2027 Part I

Challenger Brand Study 2027

Part I: A Look Back to Move Forward

Challenger Brand Study 2027

Part I: A Look Back to Move Forward

Challenger brands play an increasingly important role in reshaping the CPG landscape, capturing an outsized share of category growth and forcing established leaders to rethink how they compete. Across categories, emerging brands are winning with disruptive approaches to meeting evolving consumer needs while legacy players struggle to sustain relevance and growth.

At Seurat, we’ve spent the better part of the last decade studying challengers and the principles fueling their success. Ahead of the 2027 Challenger Brand study coming this January, we’ve looked back to move forward. We revisited brands we’ve profiled to understand what separates those that create initial disruption from those that create enduring growth, often generating enough incremental brand and category value to merit acquisition. What surfaced was a “Challenger Growth Engine”: a set of interconnected principles for creating and sustaining growth.
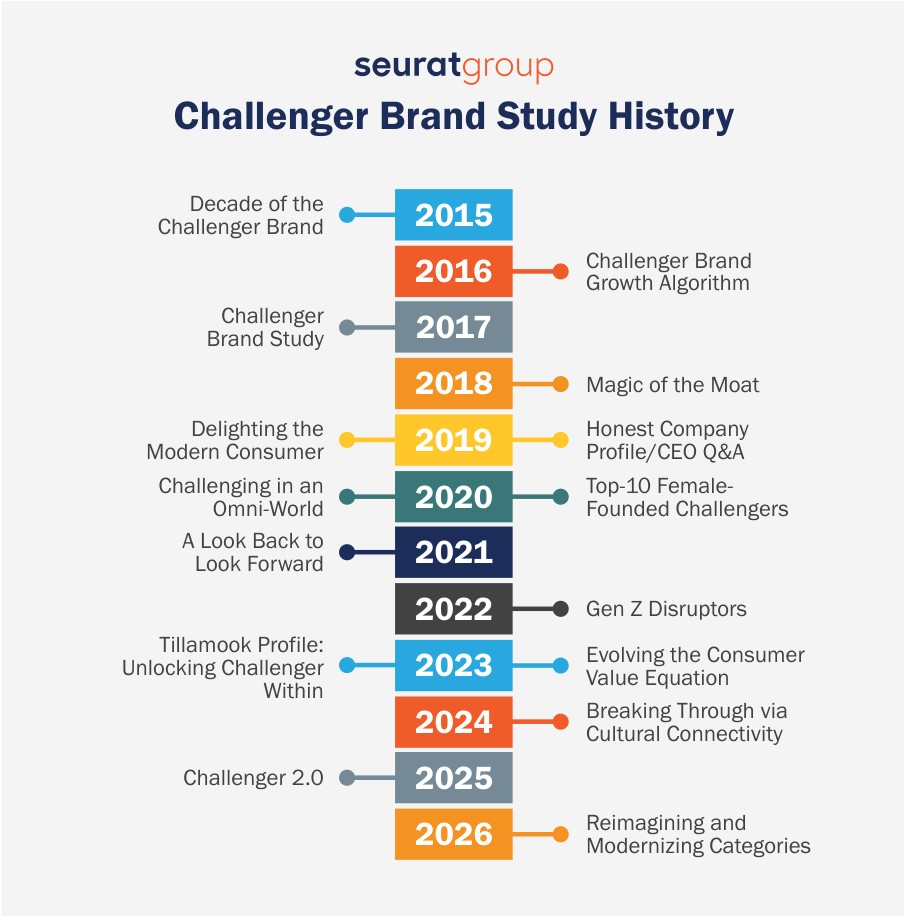
Seurat Group Challenger Brand Study History, 2015 to 2026: Decade of the Challenger Brand (2015), Challenger Brand Growth Algorithm (2016), Challenger Brand Study (2017), Magic of the Moat (2018), Delighting the Modern Consumer and Honest Company Profile/CEO Q&A (2019), Challenging in an Omni-World and Top-10 Female-Founded Challengers (2020), A Look Back to Look Forward (2021), Gen Z Disruptors (2022), Tillamook Profile: Unlocking Challenger Within and Evolving the Consumer Value Equation (2023), Breaking Through via Cultural Connectivity (2024), Challenger 2.0 (2025), Reimagining and Modernizing Categories (2026)
Seurat Challenger Brands 2019 - 2026: logos of the challenger brands Seurat Group has featured

Of the 85 brands we’ve featured since 2019, 3 in 4 have successfully sustained momentum by activating the Challenger Growth Engine1. While rooted in how emerging Challengers win, these principles offer a powerful model for all CPG brands seeking to reignite growth, strengthen consumer relevance, and uncover new opportunities within and beyond their core business. This paper unpacks the core principles of the Challenger Growth Engine with select case studies of brands that we featured when they were early Challengers.

Looking back across nearly a decade of Challenger brands reveals that success begins with (1) modernizing the value equation, going beyond traditional price, pack, and product benefits to address what consumers truly value and redefining category expectations to establish compelling reasons to choose. Challengers sustain this momentum by (2) turning trial into ritual, building lasting consumer habits by converting trial into repeat purchase and enduring brand preference. With a differentiated value proposition and a highly engaged consumer base, they (3) unlock new waves of growth by addressing emerging consumer needs, expanding into additional occasions and/or pursuing adjacent opportunities with a right to win.

1 Success was determined based on brands’ ability to expand into new categories, occasions, formats or consumer segments, supported by documented growth in revenue, market share, distribution, valuation, or acquisition following that expansion.

Modernize the Value Equation

Consumers continually assess what they get relative to what they give up, encouraging brands to deliver a more compelling balance of benefits and costs. Successful Challengers modernize the value equation in two ways: (1) optimizing the core product offering by prioritizing must-haves over wants to eliminate unnecessary costs and (2) expanding dimensions of value beyond traditional product benefits to address deeper human needs. Brands expand dimensions of value through relevance, aspiration, accessibility, and convenience, addressing evolving functional, emotional, and cultural needs. Chomps addresses both principles by delivering high-quality, all-natural protein without unnecessary ingredients found in traditional meat sticks, such as added sugars, curing agents, and synthetic casings, while providing a convenient, portable snack that makes nutritious eating fit effortlessly into busy lifestyles. By developing a more nuanced understanding of what consumers truly value, Challengers solve tensions, redefine category expectations, and create differentiated reasons to choose their brands, attracting new consumers and giving those who previously sat outside the category reasons to participate.

Turn Trial into Ritual

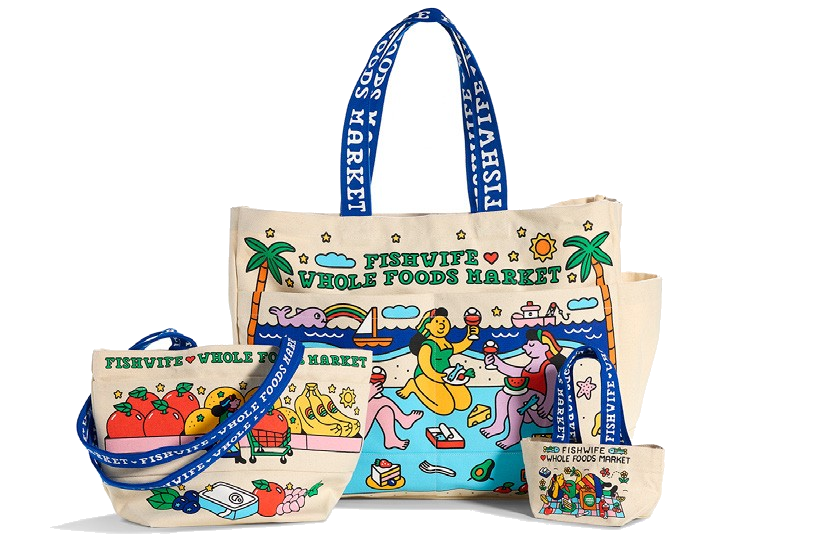
To give consumers reasons to return, brands must find ways to become a natural part of their everyday lives. This starts by making the brand easy to incorporate into existing routines, removing barriers to use through simplified preparation, improved packaging, or increased availability. Subscriptions, meaningful benefits, and other incentives can further make continued engagement convenient and rewarding. Creating seamless experiences across channels further reduces friction, making the brand easy to access, engage with, and return to. Smalls puts this principle into practice through personalized onboarding quizzes, flexible subscription deliveries, and dedicated customer service that simplify the feeding experience for cat owners. Brands can further strengthen loyalty by building genuine relationships with consumers, creating opportunities for consumers to connect with the brand and one another, and making them feel recognized and appreciated. Fishwife x Whole Foods Market limited-edition tote bag collectionThese relationships also create opportunities to better understand consumers, using behaviors and preferences to anticipate changing needs to continuously improve products, services, and experiences. Fishwife cultivates this connection through playful social media engagement and creative collaborations, including a limited-edition Whole Foods Market tote bag collection that brought the brand into consumers’ everyday routines, turning brand affinity into a visible expression of identity. The collaboration sold over 99% of inventory in its first week, demonstrating the strength of its consumer following. By adapting alongside consumers, brands can deliver increasingly relevant and personalized experiences that strengthen their role in everyday routines, becoming an essential part of consumers’ lives and creating a brand ecosystem that keeps them highly engaged.
Fuel the Perpetual Growth Engine
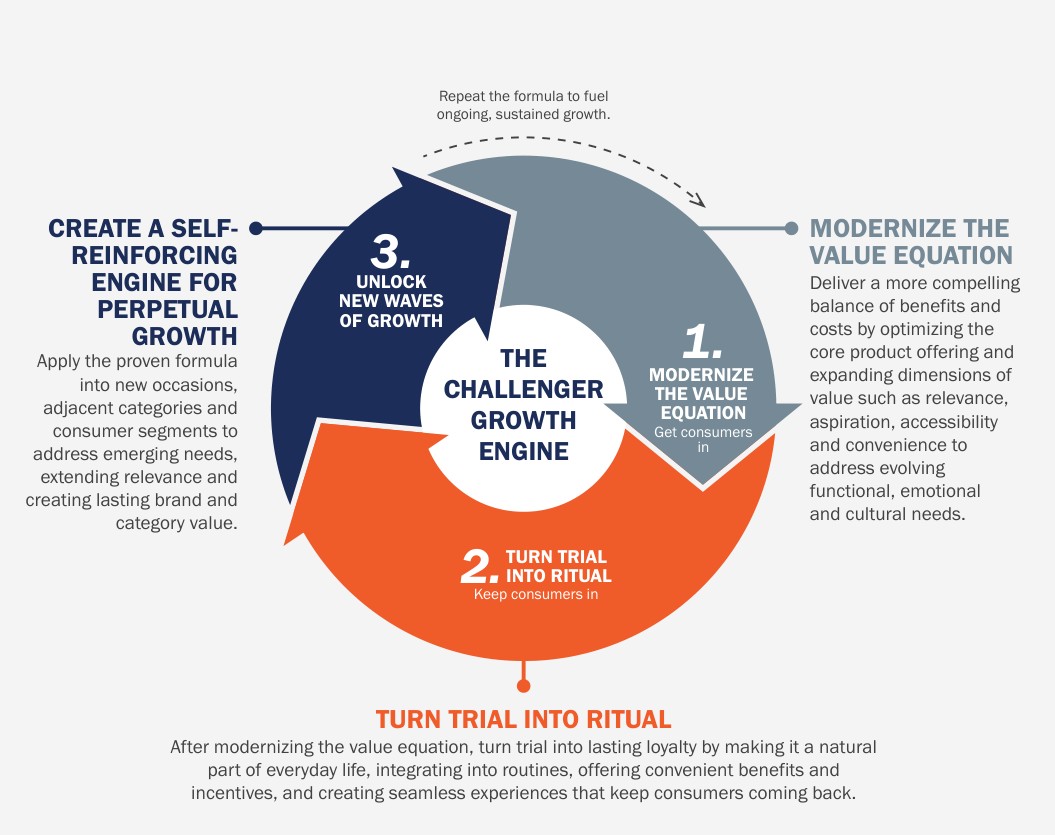
The Challenger Growth Engine. 1. Modernize the value equation (get consumers in): deliver a more compelling balance of benefits and costs. 2. Turn trial into ritual (keep consumers in): make the brand a natural part of everyday life. 3. Unlock new waves of growth: apply the proven formula to new occasions, adjacent categories and consumer segments. Repeat the formula to fuel ongoing, sustained growth.

Once Challengers have established a differentiated value proposition and turned trial into ritual, they unlock successive waves of growth by extending their model for success across new spaces. Challengers that scale achieve sustainable growth by bringing the principles of modernizing the value equation and deepening consumer relationships into new occasions, adjacent categories, and consumer segments. Rather than simply introducing new products, they identify where their existing strengths can solve new problems or meet different consumer needs. Each expansion builds on what consumers already value about the brand, creating new reasons to engage and broadening its reach. By continually applying these principles, Challengers create a self-reinforcing engine for sustained growth, keeping their brand in perpetual motion.

The following case studies demonstrate how previously featured Challenger brands have successfully activated the Challenger Growth Engine.

Case study: Siete
Siete

Featured:
2024
Valuation:
$1.2B in 2025

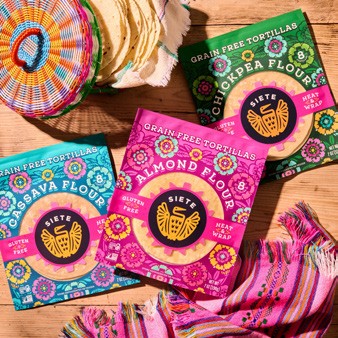
Siete was born from the founder’s desire to enjoy beloved foods while navigating dietary restrictions. What began as a homemade family solution evolved into a mission to make culturally meaningful foods accessible to more consumers. The brand introduced grain-free tortillas as an alternative to traditional flour tortillas, allowing consumers avoiding gluten or grains to enjoy familiar Mexican-American foods without compromising on taste, modernizing the value equation by eliminating a longstanding category trade-off. Siete’s proposition extended beyond allergy-friendly alternatives, weaving cultural heritage, family identity, and inclusivity into its brand to expand dimensions of value and create deeper emotional relevance among consumers. Its family-founded mission of bringing more people to the table built genuine relationships rooted in shared values, community, and belonging.
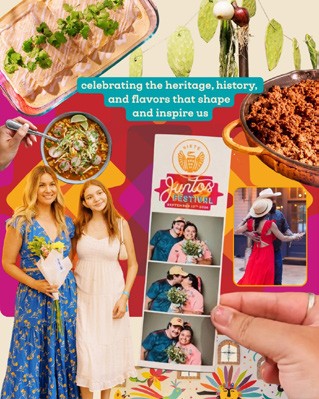
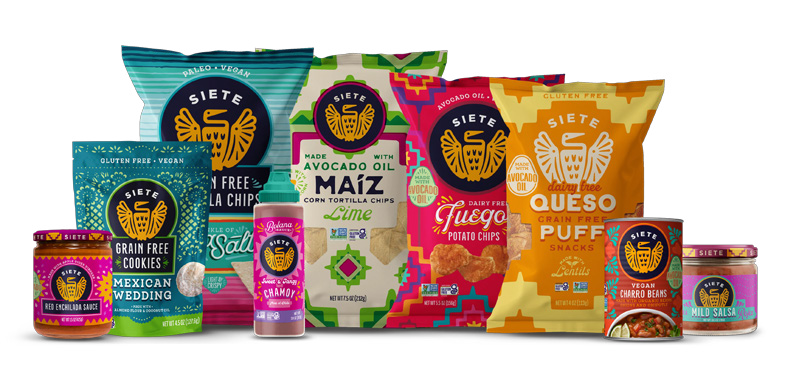
Siete brand celebration of heritage, history and flavorSiete tortilla chips, potato chips, sweet snacks, salsas and seasoningsSiete grain-free tortillas

Siete fueled its perpetual growth engine by extending its values and brand promise both within and beyond traditionally Mexican-American products, unlocking new consumption occasions through tortilla chips, potato chips, and sweet snacks. The brand then carried the same commitment to thoughtfully selected ingredients, cultural heritage, and taste into salsas, sauces, seasonings, and beans, extending its role across everyday meals. By repeatedly applying its principles of expanding value through inclusivity and fostering emotional connection, Siete transformed a solution to a specific dietary need into a broader food platform rooted in Mexican-American heritage, with a proven formula for sustained growth, culminating in its $1.2 billion acquisition by PepsiCo in 2025.


Case study: Graza
Graza

Featured:
2025
Valuation:
$450M - $600M

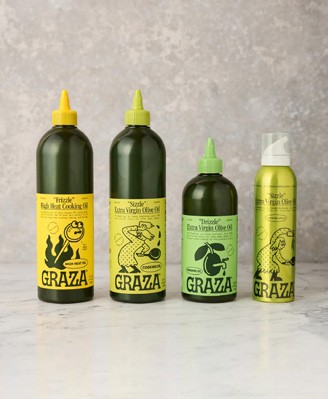
Graza Frizzle, Sizzle and Drizzle squeeze bottles and Sizzle spray
Frizzle, Sizzle, Drizzle squeeze bottles & Sizzle spray
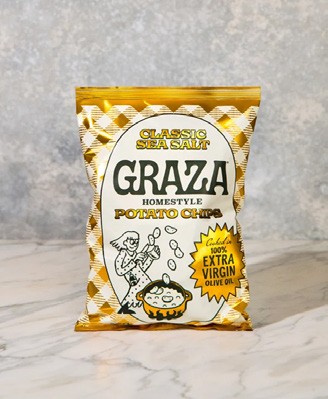
Graza olive oil potato chips

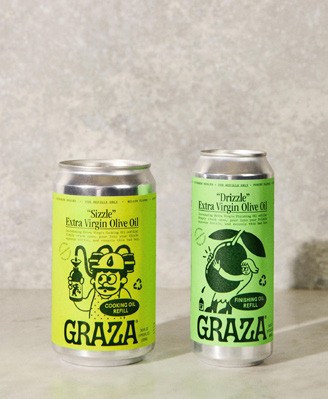
Premium olive oil has traditionally been associated with specialty cooking and provenance, often accompanied by uncertainty and confusion around quality, usage, and value. Graza entered the category with a goal to make high-quality olive oil more approachable and relevant to everyday cooking. Through playful branding, mess-free squeeze bottles, and varieties differentiated by olive harvest timing and intended use, Graza modernized the value equationGraza Sizzle and Drizzle refill cansSizzle & Drizzle refill cans by going beyond traditional product benefits to deliver greater convenience, ease of use, and a sense of fun to everyday cooking. Beyond attracting initial trial, the brand focused on building habits through specific offerings for distinct consumer jobs, including Sizzle for cooking, Drizzle for finishing, and Frizzle for high-heat cooking, alongside refill formats that encourage repeat purchase. Together, these innovations embedded Graza into consumers’ cooking routines, transforming premium olive oil from an occasional ingredient into a kitchen staple.
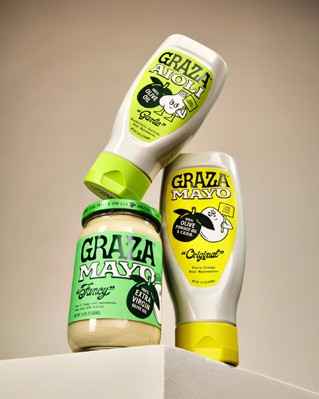
Graza mayonnaise and aioliBuilding on this differentiated proposition, Graza fueled its perpetual growth engine by extending its approach to premiumization into adjacent categories. Olive oil potato chips brought ingredient quality and sourcing into snacking, while mayonnaise and aioli carried the brand’s ingredient-first philosophy, approachable branding, and convenient formats into everyday condiments. Across these expansions, Graza continued to modernize the value equation by identifying consumer jobs to be done and building targeted solutions for habitual engagement, demonstrating how a differentiated approach to commoditized categories can unlock opportunities for growth beyond the original category.

We hope that looking back at the lessons behind the Challenger Growth Engine inspires brands of every heritage and size to unlock their Challenger within. To celebrate these principles further, Seurat Group will join Stella Rising for a webinar on December 10. Click here to register!

Stay tuned for Part II of our Challenger Brand Study in January, where we’ll identify the next wave of Challengers poised to disrupt, scale, and reshape their categories by applying new rules of disruption to succeed in an ever-changing landscape.

As always, we would love to hear from you. Let’s discuss how to apply these principles and learn more about any of our Challenger Brand studies.

Please reach out at: info@seuratgroup.com
The New Rules of Brand Selection

The New Rules of Brand Selection

The New Rules of Brand Selection

Five Questions CPG Leaders Need to Answer About AI and the Future of Commerce

Executive Summary:

The next shift in commerce will change how brands compete for shoppers’ purchases. As consumers delegate purchasing decisions to AI assistants, strong consumer preference can settle brand choice before an assistant enters, while brands left unspecified must earn their place in consideration. This gives mental and physical availability new strategic significance, raises the stakes for genuine differentiation, and could reshape the balance of power across commerce ecosystems.

This Growth Paper explores five questions to help CPG leaders understand what is changing and how to get ahead:

01
Why is this shift different?
02
Which decisions will shoppers retain or delegate?
03
How can brands build preference and win when choice remains open?
04
Which commerce players stand to gain or lose influence?
05
What does this mean for how brands build demand and invest for growth?

We close with a practical decision-influence assessment to help you identify where brand growth is exposed, evaluate competitive position, and prioritize where to invest to build advantage in the next era of commerce.

01

Why is this next shift in commerce different, and why does it matter for brands?

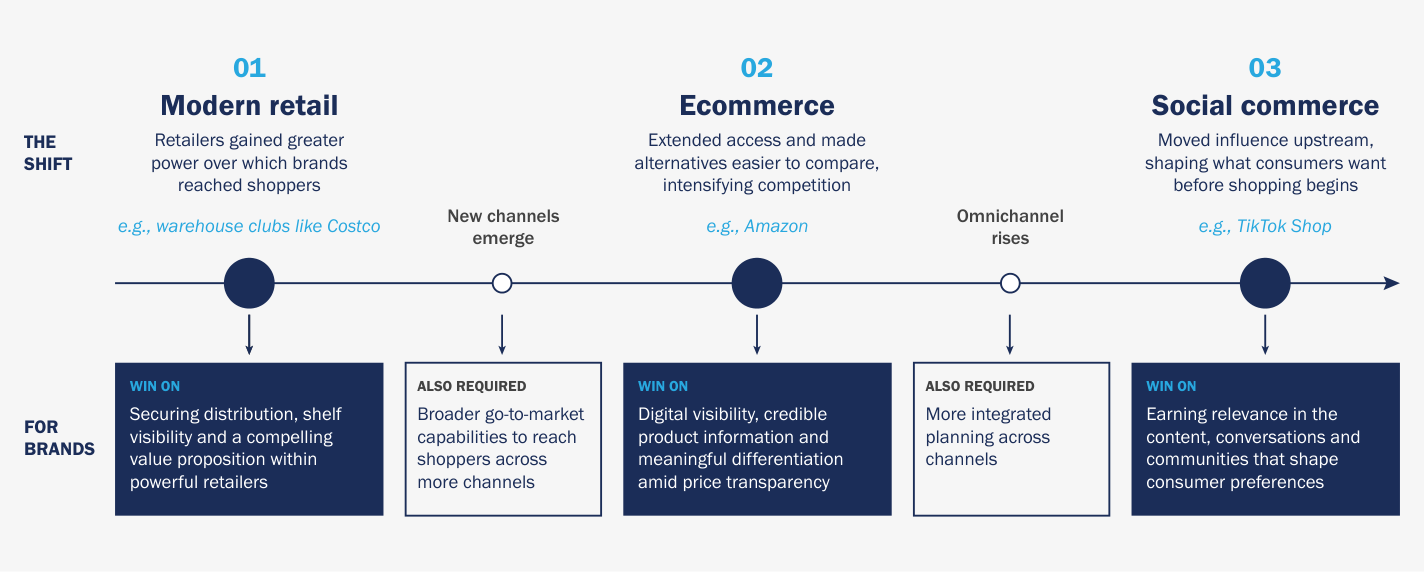
For most of the last century, the rules of CPG growth have been rewritten each time a new player came between the brand and the shopper.

Exhibit 1: Each commerce shift has moved influence closer to the moment of choice

Exhibit 1: Each commerce shift has moved influence closer to the moment of choice

The power pendulum has swung from brand owner, to retailer, to digital platform.1 Each shift created new threats and sources of advantage, changing what brands needed to do to compete for growth.

Agentic AI introduces a different kind of change. Earlier shifts changed where shoppers bought and who influenced them.2 Now, AI assistants could take on parts of the purchasing decision itself. Depending on their needs and preferences, consumers may retain control over certain decisions while delegating others to an intermediary. For brands, this creates a new competitive reality: the same purchase could play out very differently depending on which decisions the shopper has already made and which remain open to influence. The result is a redistribution of decision-making power, in which brands must compete not only for access to shoppers but for influence over the decision itself.

02

Shopping is becoming unbundled – which shopping decisions will consumers retain, and which will they delegate?

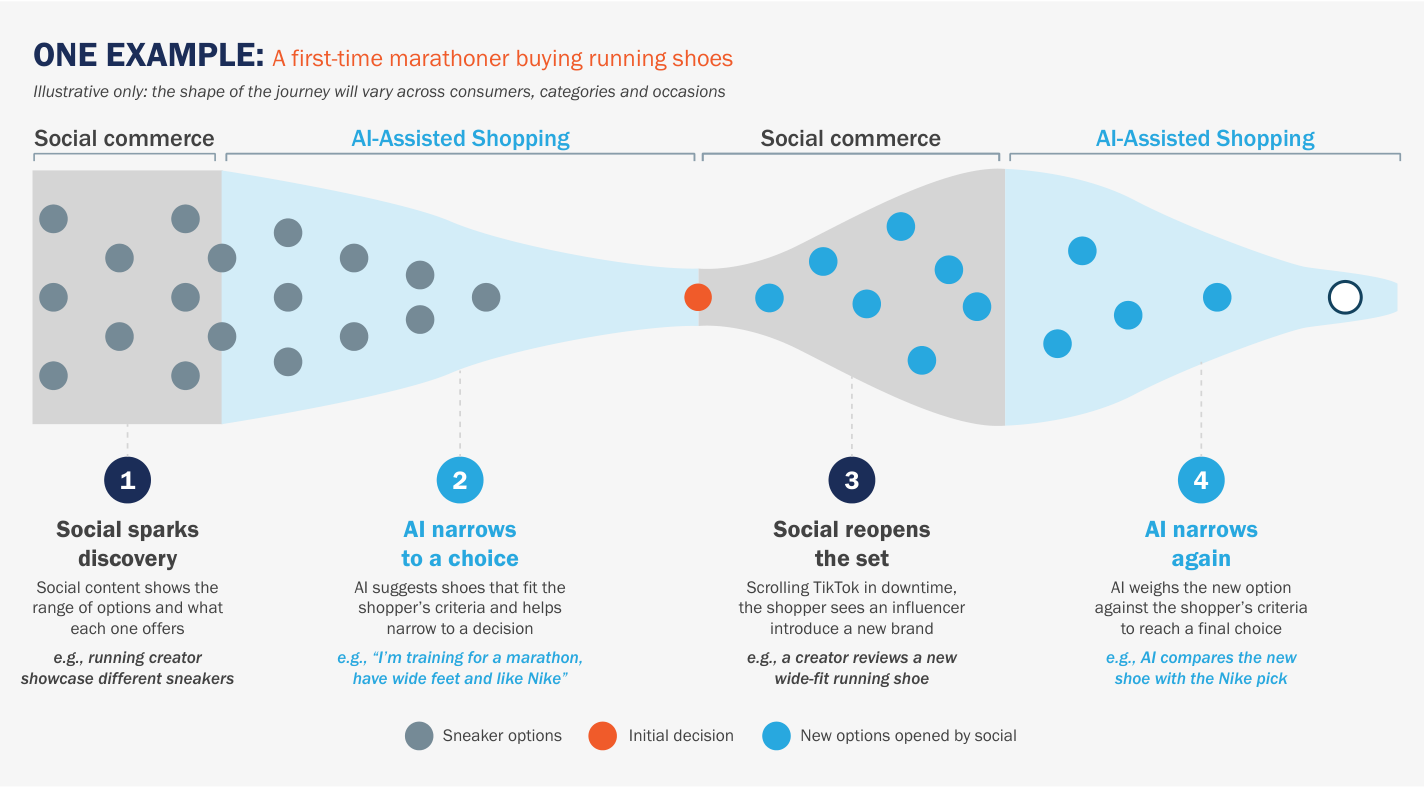
Shoppers have always varied in how much thought they give a purchase. What’s new is that they can now separate the work of shopping from the choice itself. A consumer can delegate search while retaining final choice, specify a brand while handing over execution, or define a need and allow an AI assistant to determine which product best satisfies it.3

This makes the path to purchase more fluid. A brand may generate consumer interest only to be excluded when an AI assistant narrows the options; another may enter consideration through an AI recommendation despite never having appeared on the shopper’s radar. The traditional funnel remains useful for understanding conversion, but it offers a less complete picture of competition when different actors can form, narrow, or reopen consideration, potentially without the shopper directly evaluating every alternative.4

Exhibit 2: Gaining and maintaining consideration is fluid

Exhibit 2: Gaining and maintaining consideration is fluid

Not every purchase is equally open to competition. What shoppers specify in their requests determines how much discretion the assistant has. When a shopper asks an assistant to “buy Tide,” brand selection is already settled, even if retailer, pack size, and delivery remain open. A request to “find detergent for sensitive skin” leaves brand selection unresolved, allowing the assistant to influence which products enter consideration, even if the shopper retains final choice.

03

How can brands build preference and win when choice remains open?

In AI-assisted shopping, one of the strongest positions a brand can hold is being the name in the request. Strong consumer preference can effectively settle brand choice before the assistant gets involved, while brands that aren’t specified must earn their place in consideration. Brand strength can therefore determine whether brand selection is open to competition, as well as the likelihood of winning when it is.

This gives two enduring fundamentals of brand growth, mental and physical availability, new strategic significance. Mental availability becomes a powerful means of shaping what shoppers ask for, increasing the likelihood that they specify a brand before delegating the purchase.

When brand selection remains open, brands face two hurdles: their products must be available through the retailers and commerce systems AI assistants use, and their advantages must be recognizable through accessible product information and credible, substantiated claims.

But being easy for a machine to read is not the same as being worth choosing. A strong AEO strategy can amplify a great product, but it can also make a mediocre one easier to reject. Without genuine differentiation, optimizing for machine evaluation risks shifting competition toward readily comparable attributes, price, availability, and standardized claims, driving a race to the bottom.

The more selection is automated, the more advantage shifts back to understanding how to delight consumers. Lasting differentiation depends on uncovering the unmet needs, evolving motivations, and cultural shifts that shape what consumers value. Brands must translate these insights into distinctive propositions consumers genuinely value, backed by the evidence and availability AI assistants need to recognize and recommend them.

04

Who stands to gain influence as the commerce ecosystems evolve?

As more purchasing decisions become open to influence, commerce players have growing incentives to expand their roles and shape more of what consumers ultimately buy.

Retailers are building broader ecosystems that integrate media, data, marketplaces, memberships, fulfillment, and emerging AI capabilities to shape consumer demand and behavior beyond the transaction.5 Walmart’s acquisition of VIZIO, for example, extends its advertising reach into connected TV, giving Walmart another channel in the home through which to reach and influence shoppers.6

Social and creator-commerce platforms are extending their influence into transactions: Platforms such as TikTok Shop, ShopMy and many others connect content-driven discovery to commerce, allowing them to capture more value from the demand they help create.7

AI assistants could increasingly span discovery, evaluation, recommendation, and purchase, extending their potential influence across shopping decisions.8

Together, these developments point to a growing competition among commerce players for influence over the decisions that determine what consumers buy.

05

What does this mean for how brands build demand and invest for growth?

Brands that create distinctive consumer value and architect category innovation will continue to carve out mental availability while also elevating their strategic partnership value, which increasingly depends on the decisions it influences alongside the transactions it delivers. Brands that generate consumer demand have greater leverage in these relationships, while those with less differentiated propositions risk relying on intermediaries to generate consideration and determine selection.

Customer strategy is therefore becoming inseparable from demand strategy. Choosing where to invest and which ecosystems to prioritize requires understanding:

Each ecosystem’s ability to create demand, shape choice, and influence selection

How its influence may evolve as new commerce players and models emerge

The competitive leverage brands bring to each relationship

This creates two imperatives: build consumer preference strong enough to put the brand in the shopping request, and ensure the differentiation, evidence, and availability needed to win when selection remains open.

Where to Start

Assessing where growth is exposed, and where advantage can be built

A decision-influence assessment can help brands identify where growth is at risk, how competitive dynamics may shift, and where to invest to build advantage. Four steps provide a starting point:

Assess decision exposure:

Examine shopping journeys across priority segments and identify which decisions shoppers make themselves, which they may delegate to AI assistants, and how this changes where preferences form, what drives selection, and where brands are exposed.

Map the changing balance of influence:

Develop scenarios for how retailers, platforms, creators, and AI assistants could gain or lose influence over shopper requirements, consideration, and selection. Assess how these shifts could change your brand’s routes to growth.

Evaluate your competitive position:

Identify where shoppers seek your brand and where you must compete to enter consideration. Assess whether your differentiation, claims and availability within ecosystems are strong enough to win when brand selection remains open.

Prioritize investments for advantage:

Determine your competitive strengths and gaps, then prioritize investments in brand building, innovation, shopper marketing, commerce capabilities, and ecosystem relationships based on their potential to create and capture future growth.

The brands that take advantage of the new rules for getting chosen won’t optimize for a single path to purchase. They’ll understand how decisions unfold across shoppers and intermediaries, how influence is shifting across commerce ecosystems, and build the advantage to win whether choices are made by shoppers or by intermediaries acting on their behalf.

The next era of commerce is changing how brands get chosen. Let’s identify where your brand can win.

We’re happy to talk: info@seuratgroup.com

Sources

  1. Buying Power of Multiproduct Retailers: Key Findings, Summary and Note
  2. Social Commerce
  3. Buy It in ChatGPT: Instant Checkout and the Agentic Commerce Protocol
  4. The Consumer Decision Journey
  5. Inside Walmart’s Strategy for Building an Agentic Future
  6. Walmart Completes Acquisition of VIZIO
  7. How Social Commerce Is Reshaping Ecommerce and Retail in 2026
  8. Buy It in ChatGPT: Instant Checkout and the Agentic Commerce Protocol
The Future Belongs to Brands That See It First

The Future Belongs to Brands That See It First

The Future Belongs to Brands That See It First

Why today’s forecast misses tomorrow’s shifts & how foresight reveals the blind spots in your strategy 

In 2007, BlackBerry controlled nearly half of the U.S. mobile market. When the iPhone launched that same year, BlackBerry dismissed it as a fragile gadget with no keyboard and weak security. Android joined the race in 2008, but BlackBerry didn’t release a competitive touchscreen device until 2013. By then, BlackBerry’s market share had collapsed to under 4% in the U.S.

BlackBerry wasn’t bad at making phones. It failed because it ignored the early signals of a fundamental market transformation:

Shifting identity and culture: Mobile devices were evolving from corporate work tools into expressive extensions of personal identity, status, and lifestyle.

Emerging interface innovation: Consumers were quick to embrace more intuitive, touch-first interactions over keyboard messaging.

New business models: Value expanded from selling standalone hardware to connected ecosystems pairing devices with content, apps, and other digital services.

Focused on executing day-to-day operations, BlackBerry failed to anticipate what was coming next. By the time leadership finally looked up, the market had already moved on. Most strategic plans make the same mistake. They extrapolate past successes and tweak at the margins. That approach holds up only when the future resembles the past, and it breaks the moment the landscape changes. Today, these shifts arrive faster than ever. Look at the CPG industry: challenger brands are seizing category share and redefining growth.

This is the gap that foresight is built to close.

From Insight to Foresight

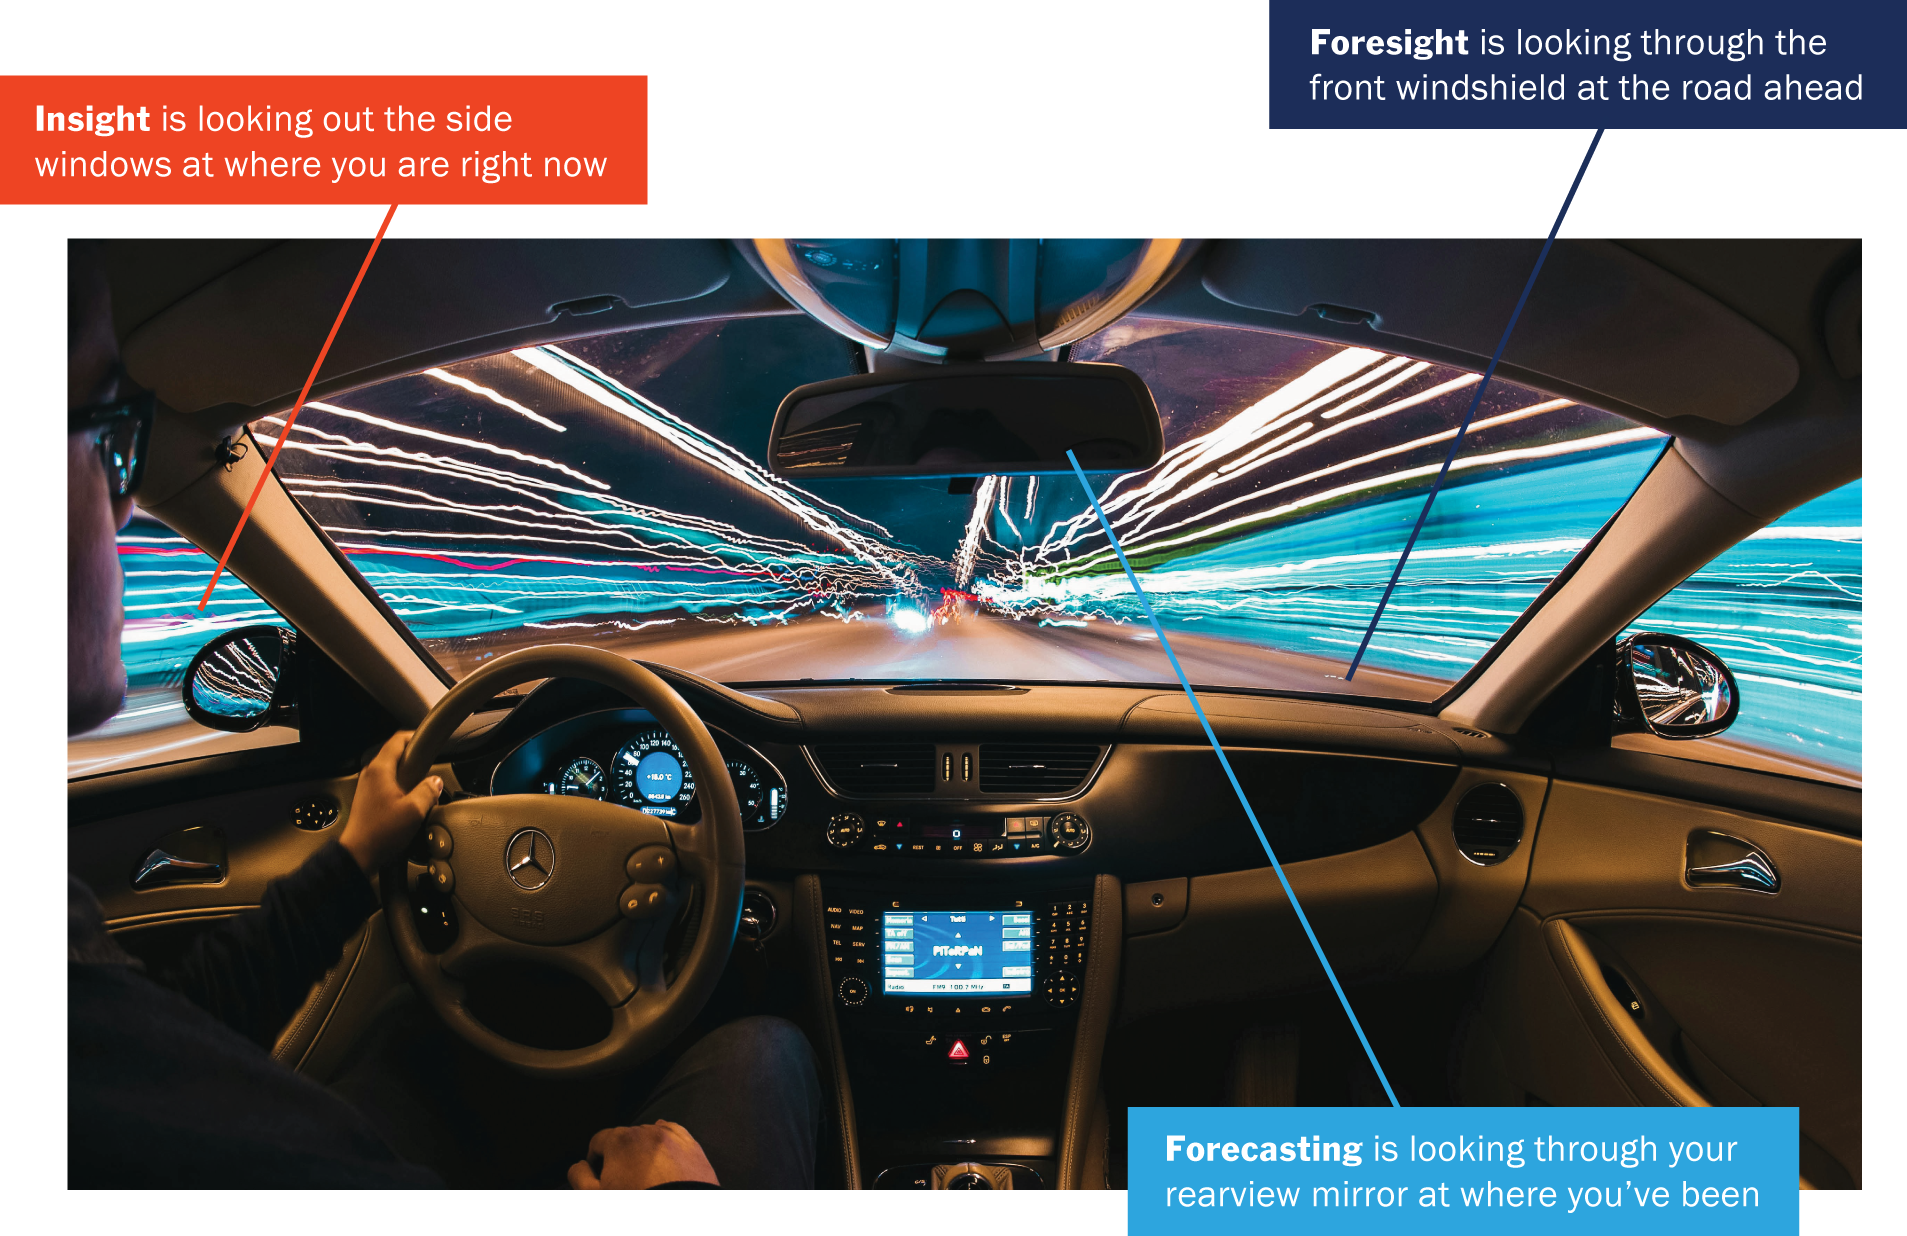
Insight explains what people want, feel, and need today, giving businesses a clear picture of the present. Forecasting takes historical data and projects it forward—reliable when conditions are slow, stable, and predictable, but brittle when they’re not. Insights and forecasts often exist in a vacuum, because consumer needs don’t change in isolation. They are shaped by external forces like technological shifts, economic pressures, and cultural swings. While insights explain why something is happening right now, and forecasts project forward what has happened in the past, foresight connects the dots between signals of change to anticipate shifts that will impact future habits, mindsets, and expectations. Think of it like driving a car:

There’s a reason the windshield dominates your view: looking behind and beside you will never show you what’s coming. Every business needs all three views, but only foresight prepares you for a world that hasn’t yet arrived.

The Cost of Flying Blind

Foresight matters because consumer beliefs are shifting, and social, technological, economic, environmental, and regulatory forces disrupt faster than ever. Past winners don’t always stay in the lead once the competition moves. The question worth asking isn’t “what will happen?” but rather “how do we grow based on what could happen?” If you skip that question, the costs compound quietly, then all at once. The organization starts making short-sighted, reactive decisions, and strategy turns into a string of urgent pivots. Organizations operating without foresight tend to fall into the same six traps:

OVER-INVESTING
Financial and human capital stay tied up in legacy products and growth models that no longer match demand.

CHASING HYPE
Copying whatever’s visible
right now, instead of building durable, differentiated platforms.

LETTING COMPETITORS
SET TERMS

Just as with BlackBerry, rivals set consumer expectations
and retailer standards before you get a chance to respond.

DILUTING BRAND EQUITY
Inconsistent communication
and random acts of innovation erode what the brand stands
for.

ERODING MARGIN
Falling behind market expectations forces you to compete on price, steadily eroding profitability and business value.

REMAINING EXPOSED TO VOLATILITY
Absent anticipation and planning, regulatory, supply,
and reputational risks become heightened.

Preparation Over Prediction

Future planning is often neglected because teams are rewarded on short-term wins and bonuses aren’t tied to next decade’s performance. That reflex only worsens in an economic downturn, when innovation and long-term strategy are often deprioritized. This is a fatal mistake. If organizations focus entirely on surviving the present, the world moves on, leaving it miles behind when the market rebounds.

The opportunity is to double down when others retreat.

That said, foresight doesn’t promise prediction, and nobody has a crystal ball. The goal is to prepare by taking actions today that position businesses and brands to win across a range of plausible futures, rather than betting everything on a single one.

Where Foresight Earns It's Keep

The best organizations don’t treat foresight as a one-time deliverable. They build it as an ongoing muscle and mindset, integrating forward-looking intelligence across the enterprise:

INNOVATION
Fuels the long-range pipeline, giving R&D a view of needs and demand drivers 2-10 years out.

BRAND STRATEGY
Shapes positioning based on where consumers, culture, and categories are headed, not where they’ve been.

CORPORATE STRATEGY
Aligns leadership and the board around a shared, evidence-based view of what’s next.

CATEGORY VISIONING
Strengthens conversations with retail partners looking for a supplier who can see around corners.

RISK MITIGATION
Surfaces regulatory, supply-chain, and reputational exposure before it becomes a crisis.

CAPABILITIES
Modernizes operating models and organizational structures to adapt to changing category dynamics.

While foresight can be leveraged across different functions, it employs the same underlying mindset: replace assumptions about the future with evidence and provide the organization with a shared language and vision for what’s next. When leadership agrees on what the future might look like, you can build a business that knows how to get there.

Why Now? Are You Prepared?

The future isn’t waiting for your next strategic planning cycle. Consumer and macro shifts are rewriting the rules of business while most organizations are busy optimizing today’s playbook.

At Seurat Group, our team is constantly scanning emerging signals of change and anticipating future shifts. Among the many forces on our radar, five stand out with strong potential to reshape consumer behavior, cultural values, and market dynamics.

Spotting Change: Five Emerging Realities Disrupting Your Growth Strategy

1. Digital Disobedience:
People are shifting from temporary digital detoxes to more active cognitive rebellion. To restore attention spans and escape algorithmic profiling, consumers are rejecting micro-content, poisoning their own data trails, and pursuing niche subcultures over curated personas. Why It Matters: Brands will need to look beyond algorithms and digital channels to meaningfully understand and reach digitally disobedient consumers.

2. Financial Rebellion:
As the promise of the American dream slips out of reach, younger generations are ditching the traditional financial playbook. Driven by a desire to game the system, their appetite for high-risk, high-reward plays—from crypto to sports betting and prediction markets—is redefining what it means to live, spend, and save. Why It Matters: Brands will fail to engage younger generations if they sell traditional value to a cohort spending and saving differently than their parents.

3. Synthetic Socialization:
People are substituting human relationships with zero-friction connections, relying on personal AI and parasocial creator bonds for closeness. While synthetic intimacy eliminates the risk of vulnerability, this reliance will accelerate solo lifestyles and deepen loneliness and social isolation.
Why It Matters: Brands will need to either adapt to the realities of an increasingly solo consumer or help facilitate experiences for deeper human connection.

4. Anti-Wellness:
People are starting to shed overly optimized habits and rigid wellness routines to reclaim joy and messiness. Exhausted by health metrics, biohacking, and “protein-maxxed” diets, consumers will prioritize unapologetic pleasure over performative wellness.
Why It Matters: Brands that fixate on wellness and optimization will lose relevance among consumers craving a more rewarding, joyful type of fulfillment.

5. Certified Human:
As hyper-convenience, automation, and AI “slop” saturate daily life, people are placing a premium on the value of human effort. From seeking out human-first experiences to raw creativity, value will continue to shift from immediacy to imperfection and the undeniable proof of human craft.
Why It Matters: As convenience becomes commoditized, more brands will need to spotlight human effort to defend their price premium.

Which of these five shifts are you actively preparing for, and which are sitting in your blind spot?
Seurat helps businesses turn these emerging risks and opportunities into prioritized actions, yielding clear strategic pathways to navigating the future.

Where to Start?

Every business is already making bets on the future. Seurat arms clients with a clear, evidence-based view of what’s coming—and a strategy built to win in whichever future arrives.

The future is already here. Let’s make sure you’re ready for it.

Interested in what the future means for your business?
Let’s talk foresight: info@seuratgroup.com
The Right Tool for the Job

The Right Tool for the Job

The Right Tool for the Job

A Framework for Using Segmentations & Demand Maps

The insights professional’s toolkit has never been more powerful: with advancements in both methodology and technology, researchers now have an unprecedented ability to build broad and deep understanding of consumers and their needs—ultimately to help businesses reach the right consumers with the right messages at the right times. Segmentations and demand maps are two of the most common tools for doing this, but unfortunately, too often these studies are commissioned as “boxes to check,” with one tool selected reflexively — or the two treated as competitors — rather than as complementary lenses calibrated to a market’s actual structure. This paper offers a practical framework for determining how to weight and combine the two so they unlock the greatest strategic leverage.

Two Tools, Two Lenses

Consumer segmentations and demand maps both bring structure to a market, but they’re designed to explain fundamentally different kinds of variation.

A consumer segmentation is designed to explain variation in the who. It segments a market according to who people are — their attitudes, behaviors, lifestyles, values, and needs as individuals. The unit of analysis is the consumer. The goal is to identify clusters of “like” people that are meaningfully different in ways that affect how they engage with a category—and, frequently, to prioritize one or more segments that are most attractive to a business.

A demand map is designed to explain variation in the why. It segments a market by why, when and/or how people consume — the jobs to be done, the emotional and functional needs at play, and the contexts in which consumption occurs. The unit of analysis is the occasion or demand moment. The goal is to reveal the architecture of consumption across a category—and, often, to prioritize a subset of demand moments for which a business has an outsized right to win.

The Variance Framework

Think of your market as having two primary dimensions along which structure can exist:

Consumer Variance: How different are the people in your category from one another in ways that matter to your brand — their needs, motivations, lifestyles, and category relationships?

Demand Variance: How different are the occasions and need states that drive consumption — the contexts, emotional drivers, and functional jobs that the category serves across different moments?

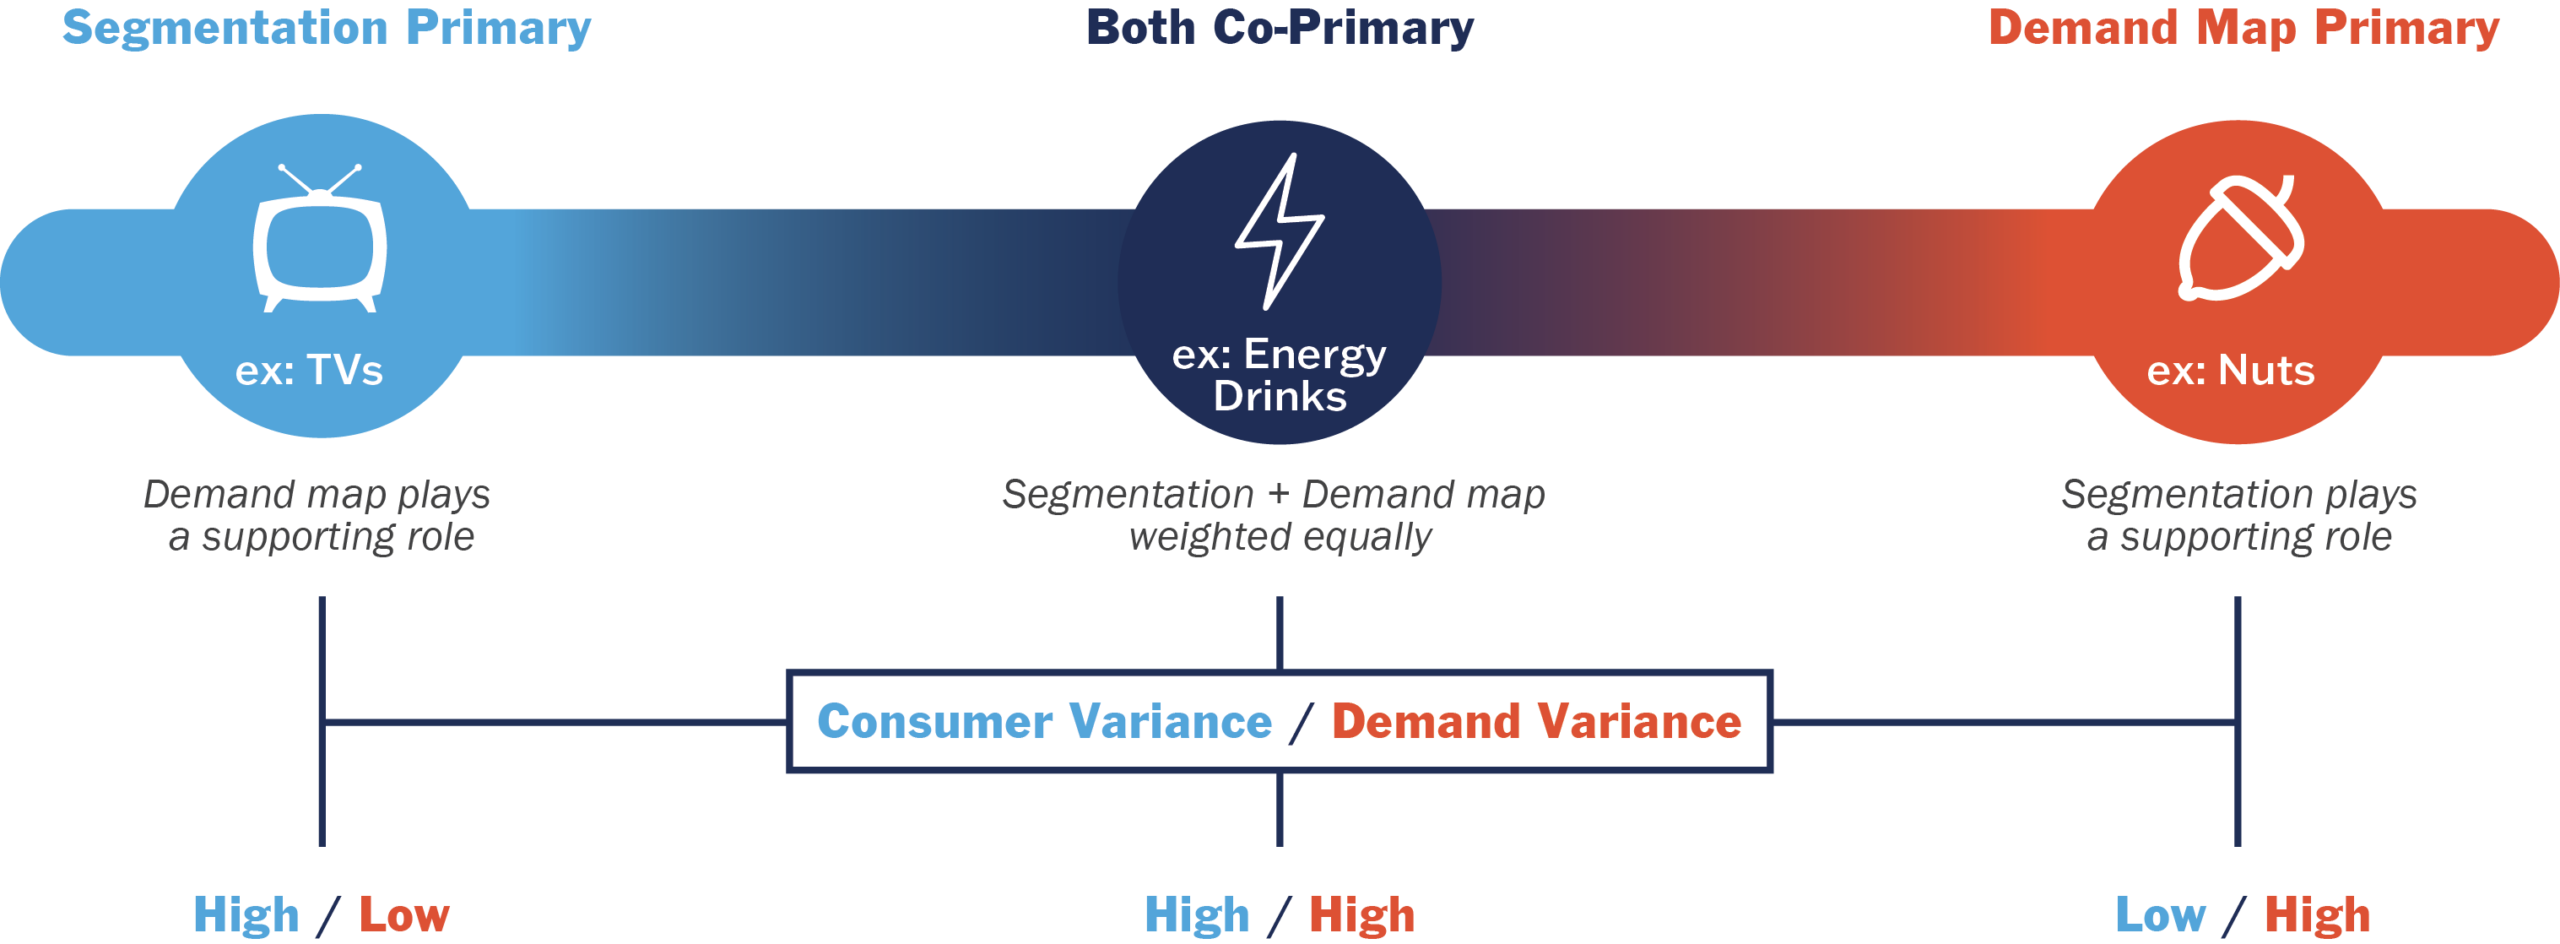
Evaluating your market on these two dimensions reveals where it sits along a spectrum. In practice, few markets sit purely at one extreme. Most have real structure on both dimensions — the question is which is more pronounced, and therefore which lens should lead. Rather than a binary choice, think of segmentation and demand mapping as anchoring two ends of a spectrum, with most markets falling somewhere between:

Wherever your market falls, the secondary lens is rarely wasted effort — it adds texture and precision to the primary lens rather than standing on its own. The question is one of emphasis and sequencing, not exclusion.

Reading the Spectrum

Segmentation as the Primary Lens

Segmentation should lead when consumption occasions are broadly consistent but the people consuming are markedly different. The category reliably serves a similar set of needs — but who shows up, and how they evaluate options, varies considerably. Here, a demand map plays a supporting role: rather than anchoring the strategy, it adds texture to how each segment engages with whatever occasion variance exists.

Consider TVs. Entertainment preferences aside, the demand occasion is relatively homogenous: a consumer is buying a screen to watch content, and it doesn’t much matter whether that screen goes in a living room, a bedroom, or a basement. The functional need is consistent across contexts. However, consumers are anything but uniform. A tech enthusiast obsessing over refresh rates and HDR standards occupies a completely different decision space than a price-conscious buyer seeking something affordable and no-frills. While a demand map would add little here, a well-crafted segmentation can shape go-to-market strategy, guide feature prioritization, and sharpen media investment. A lightweight pass at demand occasions can still sharpen the margins — knowing that the tech enthusiast is often shopping for a dedicated home-theater setup while the price-conscious buyer is furnishing a spare bedroom helps tailor messaging and channel within each segment — but it remains a supporting layer, not the primary architecture.

Demand Mapping as the Primary Lens

Demand mapping should lead when the consumer base is relatively homogenous but consumption occasions span a wide range of contexts, functional needs, and emotional drivers. The insight is less about who your consumers are and more about what they want or need in any given moment — though a secondary segmentation lens can bring clarity to marketing and communication strategy, informed by which consumers over-index on specific occasions.

Nuts offer a compelling example. Nut buyers may look different across life stage, ethnicity, household income or health & wellness orientation. However, understanding these variances does less to inform how to grow the market. Demand variance, by contrast, is significant. A consumer reaching for nuts as a between-meal snack has a different set of priorities than one choosing them as a baking ingredient, adding them as a salad topper, stirring them into oatmeal, or processing them into nut butter. Each use case implies different product formats, pack sizes, flavor profiles, price tolerances—and even in-store placement (e.g., baking aisle vs. produce department). While a segmentation alone might miss this nuance, a demand map built around the full range of use occasions should lead here, providing business owners with a framework to guide portfolio design, packaging decisions, merchandising guidelines, and occasion-specific messaging. A secondary consumer lens still adds value: knowing which cohorts over-index with which occasions can inform where and how brands “show up” and ensure messaging resonates.

Both Tools Used Together

Meaningful variance in both dimensions signals a genuinely complex market — one where neither tool alone fully captures the strategic landscape, and where the two sit at the midpoint of the spectrum. Both are warranted, and they work best together, independently segmenting consumers and demand moments and then superimposing these two lenses for a holistic view.

Energy Drinks illustrate this complexity well. Consumer variance is high: attitudes vary meaningfully toward sugar and certain ingredients, as do brand preferences (e.g., legacy mainstays vs. better-for-you challengers) and price sensitivity. These differences define fundamentally distinct ways in which consumers interact with the category.

Demand variance is equally rich. In one moment, a consumer might want a quick, intense caffeine jolt to power through a late-night work session — a high-intensity, functional occasion where format and speed of effect matter most. In another, the same consumer might want a steadier, more sustained state of calm focus. Some occasions warrant a refreshing and hydrating flavor profile that’s easy to drink quickly; others may call for something more indulgent, meant to be sipped or savored over time. Each need state or occasion calls for a different set of product attributes and reasons to believe—which are often correlated with channel (e.g., a single can purchased on-the-go at a convenience store vs. a multi-pack purchased for pantry stocking in the Club channel). A segmentation without a demand map would miss this nuance. Similarly, a demand map without a segmentation loses sight of which consumers are driving which occasions — and which are most valuable to the brand. Together they provide the full picture.

Diagnosing Your Market:

Questions to Ask Before You Commission

In summary, choosing the right tools starts with understanding where the most meaningful variance in your market lives.

Where does the meaningful variance in your market actually live — across consumers, across demand occasions, or both?

Before proceeding, ask yourself the following:

On consumer variance: When you look across your category users, do you see meaningfully different relationships with the category — different emotional drivers, different identities tied to the category, different behavioral profiles? Or does the consumer base feel relatively uniform?

On demand variance: Does the category get used in a wide range of contexts and for a wide range of reasons? Are the functional and emotional needs in one occasion genuinely different from those in another? Or are the need states relatively consistent across consumption moments?

On existing knowledge: What do you already know? If you have a recent, robust segmentation but no demand framework, the incremental return from another segmentation is low. Fill the gap in your market understanding.

On the strategic question at hand: What decision is this research intended to inform? Portfolio architecture and packaging decisions often call for demand mapping to lead. Brand positioning and targeting decisions often call for segmentation to lead. Let the decision drive which lens leads — and which plays a supporting role.

Questions to Ask Before You Commission

Calibrating the right mix of segmentation and demand mapping is one of the highest-leverage decisions an insights leader makes. Done well, it aligns your entire organization around a common language for understanding consumers and demand — and it focuses research investment where it will generate the most strategic return.

Interested in exploring the best approach for your category?
We’d love to continue the conversation: info@seuratgroup.com
Building Unreasonable Loyalty

Building Unreasonable Loyalty

Building Unreasonable Loyalty

CPG companies spend a lot of time trying to cultivate loyalty. They launch affinity-driving campaigns, track purchase rates over time, field A&Us, measure Net Promoter Score, and monitor engagement metrics across channels—all in service of winning a disproportionate share of consumers’ minds and wallets. And yet, if you subscribe to Byron Sharp’s How Brands Grow philosophy, loyalty is virtually nonexistent; the only real way to grow is through penetration. Are marketers wasting their time?

In industries like travel, hospitality and financial services, firms use rewards programs to create loyalty “beyond reason.” (Consider the choice of saving $200 on a flight or earning Platinum medallion status.) These companies tend to own customer relationships, a dynamic that affords them first-party data, richer branded experiences and the ability to control the message. With CPG brands, scaling beyond a certain point typically means relinquishing control. Absent a direct relationship, their brand story loses fidelity, and they exist at the mercy of the merchant.

And yet, some brands manage to transcend this dynamic. Despite disintermediation and with no subscription plans or fancy tiered rewards programs, a select few manage to achieve what can only be considered “unreasonable loyalty”—that is, they win consumer choice even when cheaper and more readily available alternatives exist. They simultaneously grow both penetration and share of wallet. We set out to understand how these brands cultivate unreasonable loyalty and identified a set of core principles brand builders at any stage can apply.

Achieving unreasonable loyalty comes down to three things:

Sometimes unreasonable loyalty boils down to delivering an experience that competitors simply can’t replicate. That experience could be sensory (e.g., a proprietary taste or texture), aesthetic (e.g., a visual and/or design experience that makes alternatives feel like a sacrifice) or functional (e.g., a product that works demonstrably better than anything else or ‘locks you in’ based on habit or ease).

ELLENOS is Greek yogurt with a creamy texture and mouthfeel that’s unrivaled in the category. It’s closer to Italian gelato than it is Fage, which helps explain the dessert recipes on the brand’s website and food porn on Instagram. This unique sensory experience allows ELLENOS to command a hefty premium: at $3.99 per tub, it’s more than twice the price of Chobani on a per ounce basis—and consumers are more than happy to pay up.

Hill’s Science Diet competes in dog food—not the sexy, fresh home-delivery meal kits, but brown, dry kibble. And yet, it has earned industry-leading pet parent loyalty through a combination of superior efficacy and high switching costs. Its proprietary ActivBiome+ innovation harnesses decades of scientific research to deliver noticeable immunity, digestion and vitality benefits. And once dogs eat it regularly, assuming they tolerate it well, there’s virtually no reason to ever switch. A 27.5-lb bag of Rx-grade Biome sells for $145 vs. $63 for Chewy’s private brand.

Aquaphor has built a reputation as a magic ointment, with “put some Aquaphor on it” being the go-to advice for everything from dry, cracked skin and minor scrapes and burns to diaper rash, pimples, dry cuticles and more. The product itself is just petroleum jelly that forms a breathable protective layer on the skin. But it’s a master class in building consumer loyalty and trust: a simple and safe ingredient profile, coupled with distinctive memory structures, dermatologist recommendation claim and word-of-mouth efficacy has helped fuel sustained double-digit growth for Beiersdorf’s Derma division.
Other brands cultivate unreasonable loyalty by reinforcing consumers’ sense of identity. When brands become entrenched in identity, each purchase signals allegiance to a worldview—often to the point where switching can feel like a betrayal of self, rather than a shift in preference. This is valuable territory: the higher you go on Maslow’s hierarchy of needs, the greater your ability to develop deep emotional ties and command a meaningful premium.

YETI doesn’t just sell coolers; it sells an aspirational lifestyle. Being seen with a YETI signals an ability to afford certain creature comforts (coolers can run upwards of $400) as well as participation in a rugged, suburban outdoorsy lifestyle. Loyalty comes not just from high quality products that work, but also from a deliberate focus on making buyers feel like the envy of the neighborhood—which spans everything from design to channel strategy and commitment to environmental stewardship.

Fernet Branca is an Italian amaro with a medicinal taste profile that’s proudly not for everyone. It’s powerfully bitter, with strong notes of menthol—not unlike a grownup Jägermeister. This profile, coupled with a storied Italian legacy and vintage design that looks great in dimly lit bars and restaurants, has earned it a reputation as a
“bartender’s handshake.” Ordering a Fernet signals one of two things: you’re either
a hospitality pro or an in-the-know consumer with highly discerning taste. Either way, this dynamic has propelled the brand north of $500MM, an impressive feat in a softening beverage alcohol market.

Trader Joe’s breaks nearly every rule in the grocery book. And yet, its formula of limited SKUs, majority private label products, constantly changing assortment and no discounting has created some of the industry’s most fiercely loyal shoppers. This playbook helps patrons signal that they’re savvy, value-conscious and a little less
“mainstream” in their tastes. The strategy helps explain why TJ’s boasts
industry-leading sales per square foot.

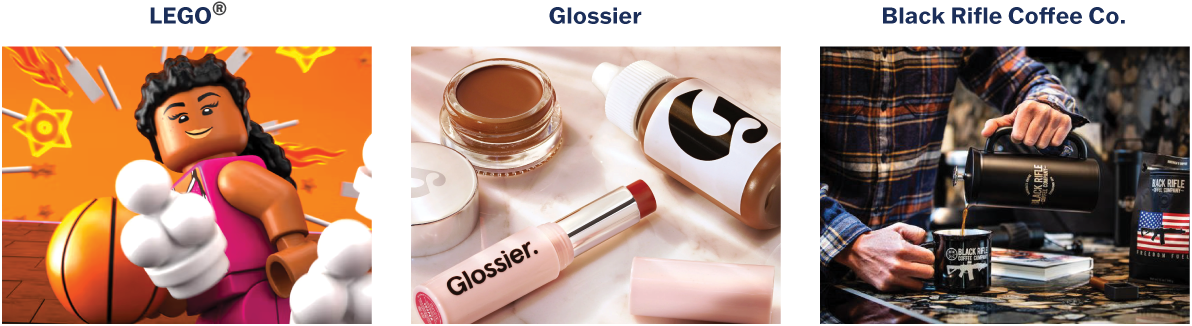
Brands also win unreasonable loyalty by building and facilitating community—appealing to consumers’ desire to belong to something larger than themselves. Some brands actively engage consumers in co-creating products and experiences; others simply invite them to participate in ways that make them feel more involved. The common thread: brand as a vehicle for human connection.

LEGO® cultivates community in a way that makes it look more like an entertainment company than a toy manufacturer. The brand uses a platform of creativity to give its intergenerational tribe of builders endless ways to connect, from in-person building events and digital forums to special edition fandom crossovers (Star Wars, Harry Potter, Marvel), TV & movie content (LEGO® Masters, The LEGO® Movie), theme parks and more. AFOL (“adult fan of LEGO®”) has even worked its way into the vernacular, further testament to the brand’s community-building power.

Glossier originated as “Into the Gloss,” a beauty blog by founder Emily Weiss, who harnessed that early, highly engaged audience to co-create the beauty brand it is today. Glossier nurtures community through a collaborative approach to brand building—iterating with consumers on product evolution & innovation, prioritizing real consumers over models in advertising, amplifying user-generated content and setting up retail stores as places to connect over shared experiences, rather than merely transact.

Black Rifle Coffee is a veteran-founded coffee company for “people who love America.” The brand is unequivocal and single-minded about its community across product naming, packaging design and its commitment to giving back to veterans, first responders, and men and women in uniform. This community is paying off: in a tough commodity category, Black Rifle grew net revenue 7% to $400MM in 2025 and scaled distribution to an impressive 55% ACV.

Looking across these examples, two things are clear about unreasonable loyalty. First, the most successful brands aren’t asking, “how do we keep you buying?” but rather, “how do we keep you believing?” Second, the secret isn’t owning the relationship—it’s owning the story consumers tell themselves. At scale, brands that crack this do it by finding channels—not retail channels, but cultural channels—where that story keeps getting reinforced.

Interested in exploring how your brand can cultivate unreasonable loyalty?
Let’s talk about what’s possible: Let’s discuss: info@seuratgroup.com.