Challenger Brand Study 2027, Part I: A Look Back to Move Forward

Challenger Brand Study 2027, Part I: A Look Back to Move Forward
A magnifying glass over a blurred city at night, the cover of Challenger Brand Study 2027 Part I

Challenger Brand Study 2027

Part I: A Look Back to Move Forward

Challenger Brand Study 2027

Part I: A Look Back to Move Forward

Challenger brands play an increasingly important role in reshaping the CPG landscape, capturing an outsized share of category growth and forcing established leaders to rethink how they compete. Across categories, emerging brands are winning with disruptive approaches to meeting evolving consumer needs while legacy players struggle to sustain relevance and growth.

At Seurat, we’ve spent the better part of the last decade studying challengers and the principles fueling their success. Ahead of the 2027 Challenger Brand study coming this January, we’ve looked back to move forward. We revisited brands we’ve profiled to understand what separates those that create initial disruption from those that create enduring growth, often generating enough incremental brand and category value to merit acquisition. What surfaced was a “Challenger Growth Engine”: a set of interconnected principles for creating and sustaining growth.
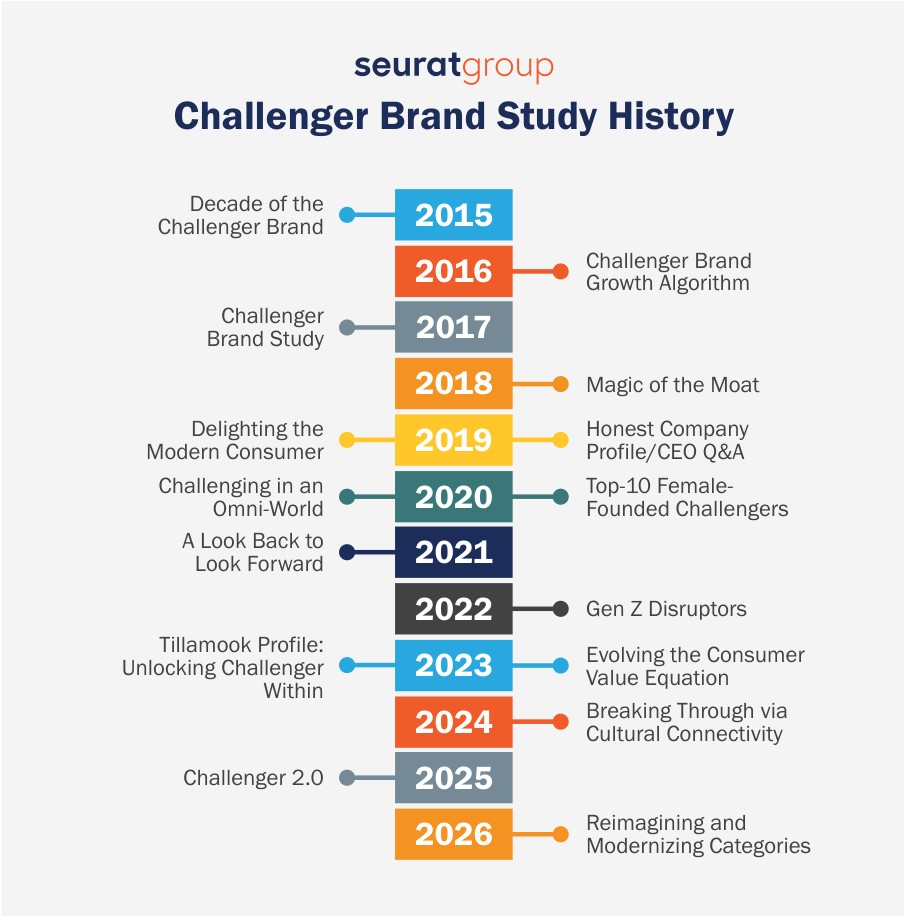
Seurat Group Challenger Brand Study History, 2015 to 2026: Decade of the Challenger Brand (2015), Challenger Brand Growth Algorithm (2016), Challenger Brand Study (2017), Magic of the Moat (2018), Delighting the Modern Consumer and Honest Company Profile/CEO Q&A (2019), Challenging in an Omni-World and Top-10 Female-Founded Challengers (2020), A Look Back to Look Forward (2021), Gen Z Disruptors (2022), Tillamook Profile: Unlocking Challenger Within and Evolving the Consumer Value Equation (2023), Breaking Through via Cultural Connectivity (2024), Challenger 2.0 (2025), Reimagining and Modernizing Categories (2026)
Seurat Challenger Brands 2019 - 2026: logos of the challenger brands Seurat Group has featured

Of the 85 brands we’ve featured since 2019, 3 in 4 have successfully sustained momentum by activating the Challenger Growth Engine1. While rooted in how emerging Challengers win, these principles offer a powerful model for all CPG brands seeking to reignite growth, strengthen consumer relevance, and uncover new opportunities within and beyond their core business. This paper unpacks the core principles of the Challenger Growth Engine with select case studies of brands that we featured when they were early Challengers.

Looking back across nearly a decade of Challenger brands reveals that success begins with (1) modernizing the value equation, going beyond traditional price, pack, and product benefits to address what consumers truly value and redefining category expectations to establish compelling reasons to choose. Challengers sustain this momentum by (2) turning trial into ritual, building lasting consumer habits by converting trial into repeat purchase and enduring brand preference. With a differentiated value proposition and a highly engaged consumer base, they (3) unlock new waves of growth by addressing emerging consumer needs, expanding into additional occasions and/or pursuing adjacent opportunities with a right to win.

1 Success was determined based on brands’ ability to expand into new categories, occasions, formats or consumer segments, supported by documented growth in revenue, market share, distribution, valuation, or acquisition following that expansion.

Modernize the Value Equation

Consumers continually assess what they get relative to what they give up, encouraging brands to deliver a more compelling balance of benefits and costs. Successful Challengers modernize the value equation in two ways: (1) optimizing the core product offering by prioritizing must-haves over wants to eliminate unnecessary costs and (2) expanding dimensions of value beyond traditional product benefits to address deeper human needs. Brands expand dimensions of value through relevance, aspiration, accessibility, and convenience, addressing evolving functional, emotional, and cultural needs. Chomps addresses both principles by delivering high-quality, all-natural protein without unnecessary ingredients found in traditional meat sticks, such as added sugars, curing agents, and synthetic casings, while providing a convenient, portable snack that makes nutritious eating fit effortlessly into busy lifestyles. By developing a more nuanced understanding of what consumers truly value, Challengers solve tensions, redefine category expectations, and create differentiated reasons to choose their brands, attracting new consumers and giving those who previously sat outside the category reasons to participate.

Turn Trial into Ritual

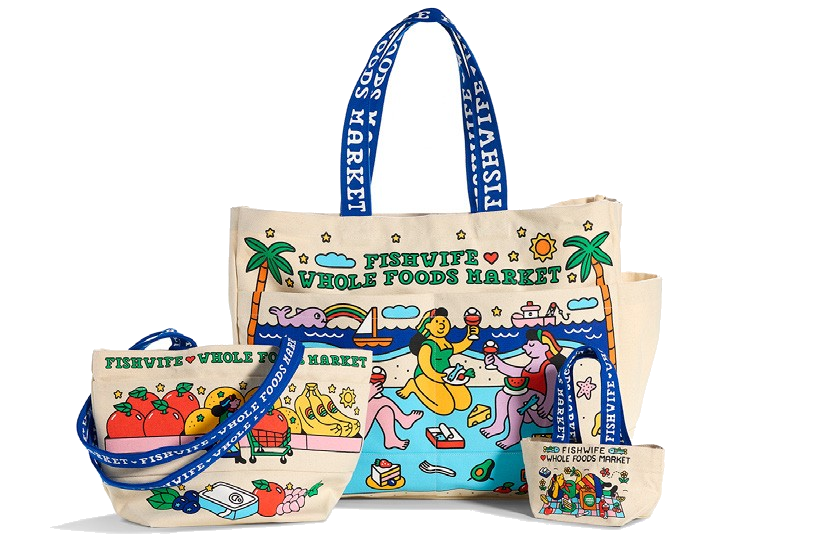
To give consumers reasons to return, brands must find ways to become a natural part of their everyday lives. This starts by making the brand easy to incorporate into existing routines, removing barriers to use through simplified preparation, improved packaging, or increased availability. Subscriptions, meaningful benefits, and other incentives can further make continued engagement convenient and rewarding. Creating seamless experiences across channels further reduces friction, making the brand easy to access, engage with, and return to. Smalls puts this principle into practice through personalized onboarding quizzes, flexible subscription deliveries, and dedicated customer service that simplify the feeding experience for cat owners. Brands can further strengthen loyalty by building genuine relationships with consumers, creating opportunities for consumers to connect with the brand and one another, and making them feel recognized and appreciated. Fishwife x Whole Foods Market limited-edition tote bag collectionThese relationships also create opportunities to better understand consumers, using behaviors and preferences to anticipate changing needs to continuously improve products, services, and experiences. Fishwife cultivates this connection through playful social media engagement and creative collaborations, including a limited-edition Whole Foods Market tote bag collection that brought the brand into consumers’ everyday routines, turning brand affinity into a visible expression of identity. The collaboration sold over 99% of inventory in its first week, demonstrating the strength of its consumer following. By adapting alongside consumers, brands can deliver increasingly relevant and personalized experiences that strengthen their role in everyday routines, becoming an essential part of consumers’ lives and creating a brand ecosystem that keeps them highly engaged.
Fuel the Perpetual Growth Engine
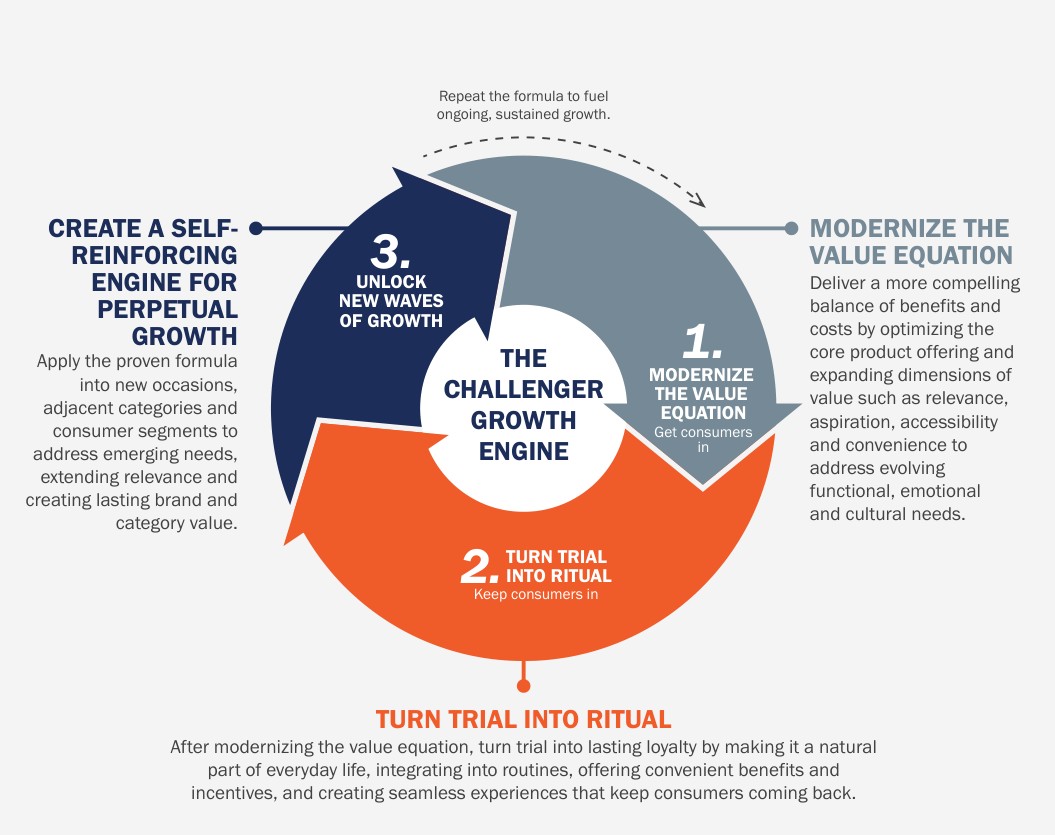
The Challenger Growth Engine. 1. Modernize the value equation (get consumers in): deliver a more compelling balance of benefits and costs. 2. Turn trial into ritual (keep consumers in): make the brand a natural part of everyday life. 3. Unlock new waves of growth: apply the proven formula to new occasions, adjacent categories and consumer segments. Repeat the formula to fuel ongoing, sustained growth.

Once Challengers have established a differentiated value proposition and turned trial into ritual, they unlock successive waves of growth by extending their model for success across new spaces. Challengers that scale achieve sustainable growth by bringing the principles of modernizing the value equation and deepening consumer relationships into new occasions, adjacent categories, and consumer segments. Rather than simply introducing new products, they identify where their existing strengths can solve new problems or meet different consumer needs. Each expansion builds on what consumers already value about the brand, creating new reasons to engage and broadening its reach. By continually applying these principles, Challengers create a self-reinforcing engine for sustained growth, keeping their brand in perpetual motion.

The following case studies demonstrate how previously featured Challenger brands have successfully activated the Challenger Growth Engine.

Case study: Siete
Siete

Featured:
2024
Valuation:
$1.2B in 2025

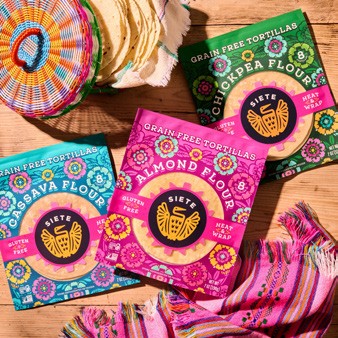
Siete was born from the founder’s desire to enjoy beloved foods while navigating dietary restrictions. What began as a homemade family solution evolved into a mission to make culturally meaningful foods accessible to more consumers. The brand introduced grain-free tortillas as an alternative to traditional flour tortillas, allowing consumers avoiding gluten or grains to enjoy familiar Mexican-American foods without compromising on taste, modernizing the value equation by eliminating a longstanding category trade-off. Siete’s proposition extended beyond allergy-friendly alternatives, weaving cultural heritage, family identity, and inclusivity into its brand to expand dimensions of value and create deeper emotional relevance among consumers. Its family-founded mission of bringing more people to the table built genuine relationships rooted in shared values, community, and belonging.
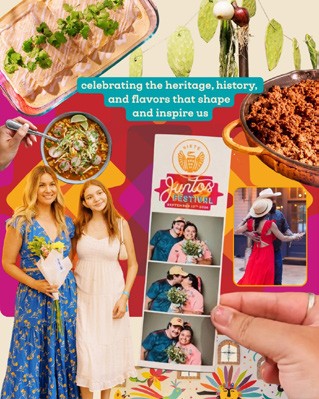
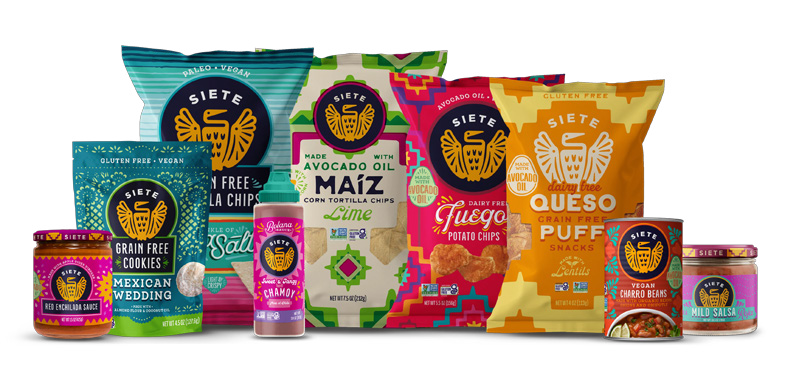
Siete brand celebration of heritage, history and flavorSiete tortilla chips, potato chips, sweet snacks, salsas and seasoningsSiete grain-free tortillas

Siete fueled its perpetual growth engine by extending its values and brand promise both within and beyond traditionally Mexican-American products, unlocking new consumption occasions through tortilla chips, potato chips, and sweet snacks. The brand then carried the same commitment to thoughtfully selected ingredients, cultural heritage, and taste into salsas, sauces, seasonings, and beans, extending its role across everyday meals. By repeatedly applying its principles of expanding value through inclusivity and fostering emotional connection, Siete transformed a solution to a specific dietary need into a broader food platform rooted in Mexican-American heritage, with a proven formula for sustained growth, culminating in its $1.2 billion acquisition by PepsiCo in 2025.


Case study: Graza
Graza

Featured:
2025
Valuation:
$450M - $600M

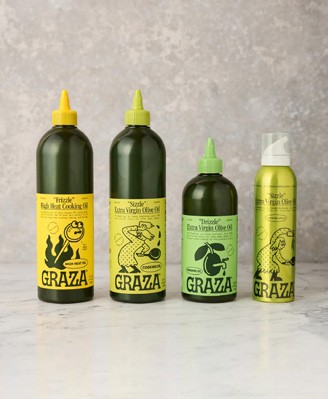
Graza Frizzle, Sizzle and Drizzle squeeze bottles and Sizzle spray
Frizzle, Sizzle, Drizzle squeeze bottles & Sizzle spray
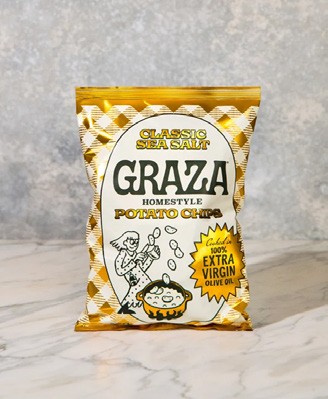
Graza olive oil potato chips

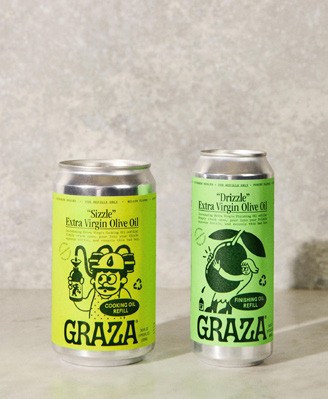
Premium olive oil has traditionally been associated with specialty cooking and provenance, often accompanied by uncertainty and confusion around quality, usage, and value. Graza entered the category with a goal to make high-quality olive oil more approachable and relevant to everyday cooking. Through playful branding, mess-free squeeze bottles, and varieties differentiated by olive harvest timing and intended use, Graza modernized the value equationGraza Sizzle and Drizzle refill cansSizzle & Drizzle refill cans by going beyond traditional product benefits to deliver greater convenience, ease of use, and a sense of fun to everyday cooking. Beyond attracting initial trial, the brand focused on building habits through specific offerings for distinct consumer jobs, including Sizzle for cooking, Drizzle for finishing, and Frizzle for high-heat cooking, alongside refill formats that encourage repeat purchase. Together, these innovations embedded Graza into consumers’ cooking routines, transforming premium olive oil from an occasional ingredient into a kitchen staple.
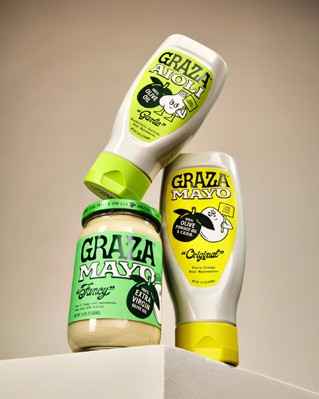
Graza mayonnaise and aioliBuilding on this differentiated proposition, Graza fueled its perpetual growth engine by extending its approach to premiumization into adjacent categories. Olive oil potato chips brought ingredient quality and sourcing into snacking, while mayonnaise and aioli carried the brand’s ingredient-first philosophy, approachable branding, and convenient formats into everyday condiments. Across these expansions, Graza continued to modernize the value equation by identifying consumer jobs to be done and building targeted solutions for habitual engagement, demonstrating how a differentiated approach to commoditized categories can unlock opportunities for growth beyond the original category.

We hope that looking back at the lessons behind the Challenger Growth Engine inspires brands of every heritage and size to unlock their Challenger within. To celebrate these principles further, Seurat Group will join Stella Rising for a webinar on December 10. Click here to register!

Stay tuned for Part II of our Challenger Brand Study in January, where we’ll identify the next wave of Challengers poised to disrupt, scale, and reshape their categories by applying new rules of disruption to succeed in an ever-changing landscape.

As always, we would love to hear from you. Let’s discuss how to apply these principles and learn more about any of our Challenger Brand studies.

Please reach out at: info@seuratgroup.com
Building Unreasonable Loyalty

Building Unreasonable Loyalty

Building Unreasonable Loyalty

CPG companies spend a lot of time trying to cultivate loyalty. They launch affinity-driving campaigns, track purchase rates over time, field A&Us, measure Net Promoter Score, and monitor engagement metrics across channels—all in service of winning a disproportionate share of consumers’ minds and wallets. And yet, if you subscribe to Byron Sharp’s How Brands Grow philosophy, loyalty is virtually nonexistent; the only real way to grow is through penetration. Are marketers wasting their time?

In industries like travel, hospitality and financial services, firms use rewards programs to create loyalty “beyond reason.” (Consider the choice of saving $200 on a flight or earning Platinum medallion status.) These companies tend to own customer relationships, a dynamic that affords them first-party data, richer branded experiences and the ability to control the message. With CPG brands, scaling beyond a certain point typically means relinquishing control. Absent a direct relationship, their brand story loses fidelity, and they exist at the mercy of the merchant.

And yet, some brands manage to transcend this dynamic. Despite disintermediation and with no subscription plans or fancy tiered rewards programs, a select few manage to achieve what can only be considered “unreasonable loyalty”—that is, they win consumer choice even when cheaper and more readily available alternatives exist. They simultaneously grow both penetration and share of wallet. We set out to understand how these brands cultivate unreasonable loyalty and identified a set of core principles brand builders at any stage can apply.

Achieving unreasonable loyalty comes down to three things:

Sometimes unreasonable loyalty boils down to delivering an experience that competitors simply can’t replicate. That experience could be sensory (e.g., a proprietary taste or texture), aesthetic (e.g., a visual and/or design experience that makes alternatives feel like a sacrifice) or functional (e.g., a product that works demonstrably better than anything else or ‘locks you in’ based on habit or ease).

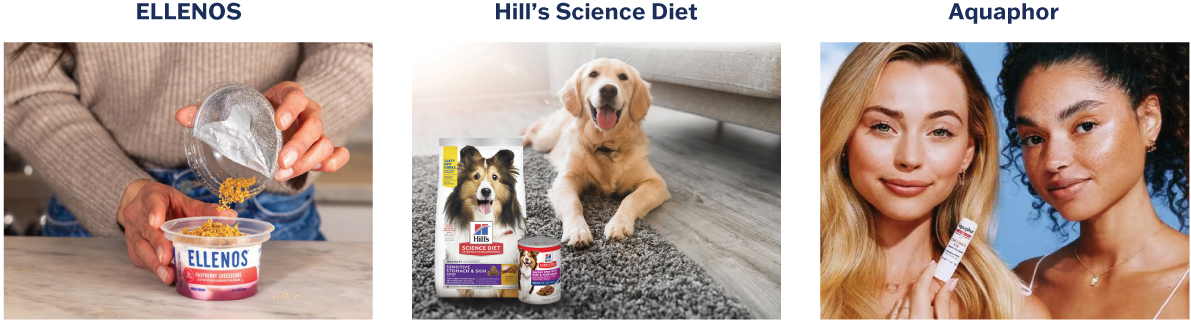
ELLENOS is Greek yogurt with a creamy texture and mouthfeel that’s unrivaled in the category. It’s closer to Italian gelato than it is Fage, which helps explain the dessert recipes on the brand’s website and food porn on Instagram. This unique sensory experience allows ELLENOS to command a hefty premium: at $3.99 per tub, it’s more than twice the price of Chobani on a per ounce basis—and consumers are more than happy to pay up.

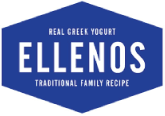
Hill’s Science Diet competes in dog food—not the sexy, fresh home-delivery meal kits, but brown, dry kibble. And yet, it has earned industry-leading pet parent loyalty through a combination of superior efficacy and high switching costs. Its proprietary ActivBiome+ innovation harnesses decades of scientific research to deliver noticeable immunity, digestion and vitality benefits. And once dogs eat it regularly, assuming they tolerate it well, there’s virtually no reason to ever switch. A 27.5-lb bag of Rx-grade Biome sells for $145 vs. $63 for Chewy’s private brand.

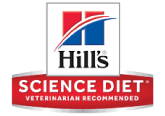
Aquaphor has built a reputation as a magic ointment, with “put some Aquaphor on it” being the go-to advice for everything from dry, cracked skin and minor scrapes and burns to diaper rash, pimples, dry cuticles and more. The product itself is just petroleum jelly that forms a breathable protective layer on the skin. But it’s a master class in building consumer loyalty and trust: a simple and safe ingredient profile, coupled with distinctive memory structures, dermatologist recommendation claim and word-of-mouth efficacy has helped fuel sustained double-digit growth for Beiersdorf’s Derma division.
Other brands cultivate unreasonable loyalty by reinforcing consumers’ sense of identity. When brands become entrenched in identity, each purchase signals allegiance to a worldview—often to the point where switching can feel like a betrayal of self, rather than a shift in preference. This is valuable territory: the higher you go on Maslow’s hierarchy of needs, the greater your ability to develop deep emotional ties and command a meaningful premium.

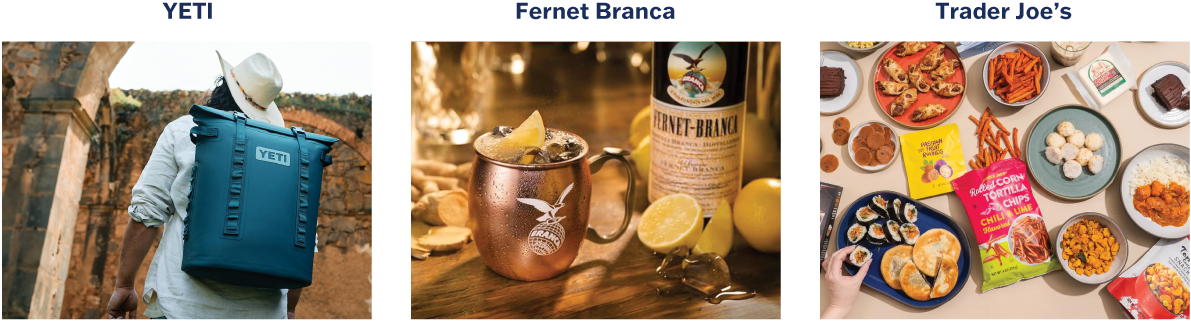
YETI doesn’t just sell coolers; it sells an aspirational lifestyle. Being seen with a YETI signals an ability to afford certain creature comforts (coolers can run upwards of $400) as well as participation in a rugged, suburban outdoorsy lifestyle. Loyalty comes not just from high quality products that work, but also from a deliberate focus on making buyers feel like the envy of the neighborhood—which spans everything from design to channel strategy and commitment to environmental stewardship.

Fernet Branca is an Italian amaro with a medicinal taste profile that’s proudly not for everyone. It’s powerfully bitter, with strong notes of menthol—not unlike a grownup Jägermeister. This profile, coupled with a storied Italian legacy and vintage design that looks great in dimly lit bars and restaurants, has earned it a reputation as a
“bartender’s handshake.” Ordering a Fernet signals one of two things: you’re either
a hospitality pro or an in-the-know consumer with highly discerning taste. Either way, this dynamic has propelled the brand north of $500MM, an impressive feat in a softening beverage alcohol market.

Trader Joe’s breaks nearly every rule in the grocery book. And yet, its formula of limited SKUs, majority private label products, constantly changing assortment and no discounting has created some of the industry’s most fiercely loyal shoppers. This playbook helps patrons signal that they’re savvy, value-conscious and a little less
“mainstream” in their tastes. The strategy helps explain why TJ’s boasts
industry-leading sales per square foot.

Brands also win unreasonable loyalty by building and facilitating community—appealing to consumers’ desire to belong to something larger than themselves. Some brands actively engage consumers in co-creating products and experiences; others simply invite them to participate in ways that make them feel more involved. The common thread: brand as a vehicle for human connection.

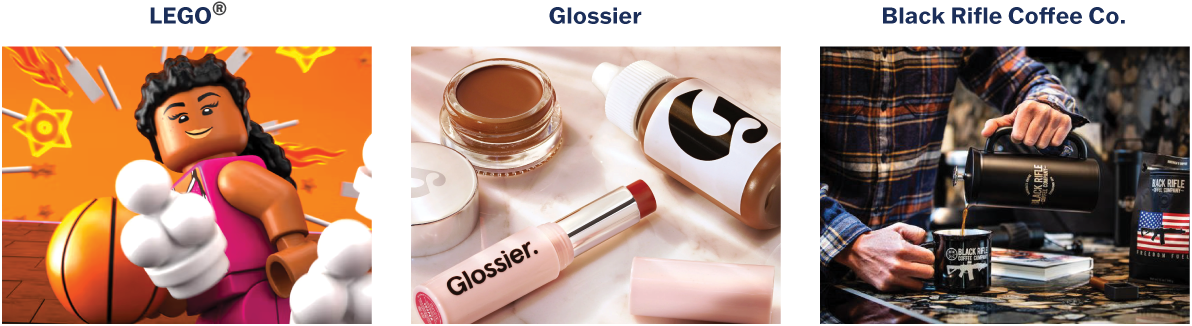
LEGO® cultivates community in a way that makes it look more like an entertainment company than a toy manufacturer. The brand uses a platform of creativity to give its intergenerational tribe of builders endless ways to connect, from in-person building events and digital forums to special edition fandom crossovers (Star Wars, Harry Potter, Marvel), TV & movie content (LEGO® Masters, The LEGO® Movie), theme parks and more. AFOL (“adult fan of LEGO®”) has even worked its way into the vernacular, further testament to the brand’s community-building power.

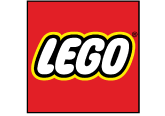
Glossier originated as “Into the Gloss,” a beauty blog by founder Emily Weiss, who harnessed that early, highly engaged audience to co-create the beauty brand it is today. Glossier nurtures community through a collaborative approach to brand building—iterating with consumers on product evolution & innovation, prioritizing real consumers over models in advertising, amplifying user-generated content and setting up retail stores as places to connect over shared experiences, rather than merely transact.

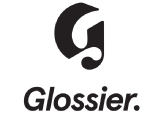
Black Rifle Coffee is a veteran-founded coffee company for “people who love America.” The brand is unequivocal and single-minded about its community across product naming, packaging design and its commitment to giving back to veterans, first responders, and men and women in uniform. This community is paying off: in a tough commodity category, Black Rifle grew net revenue 7% to $400MM in 2025 and scaled distribution to an impressive 55% ACV.

Looking across these examples, two things are clear about unreasonable loyalty. First, the most successful brands aren’t asking, “how do we keep you buying?” but rather, “how do we keep you believing?” Second, the secret isn’t owning the relationship—it’s owning the story consumers tell themselves. At scale, brands that crack this do it by finding channels—not retail channels, but cultural channels—where that story keeps getting reinforced.

Interested in exploring how your brand can cultivate unreasonable loyalty?
Let’s talk about what’s possible: Let’s discuss: info@seuratgroup.com.

Inside Expo West 2026: The Trends That Matter

Inside Expo West 2026: The Trends That Matter

Inside Expo West 2026: The Trends That Matter

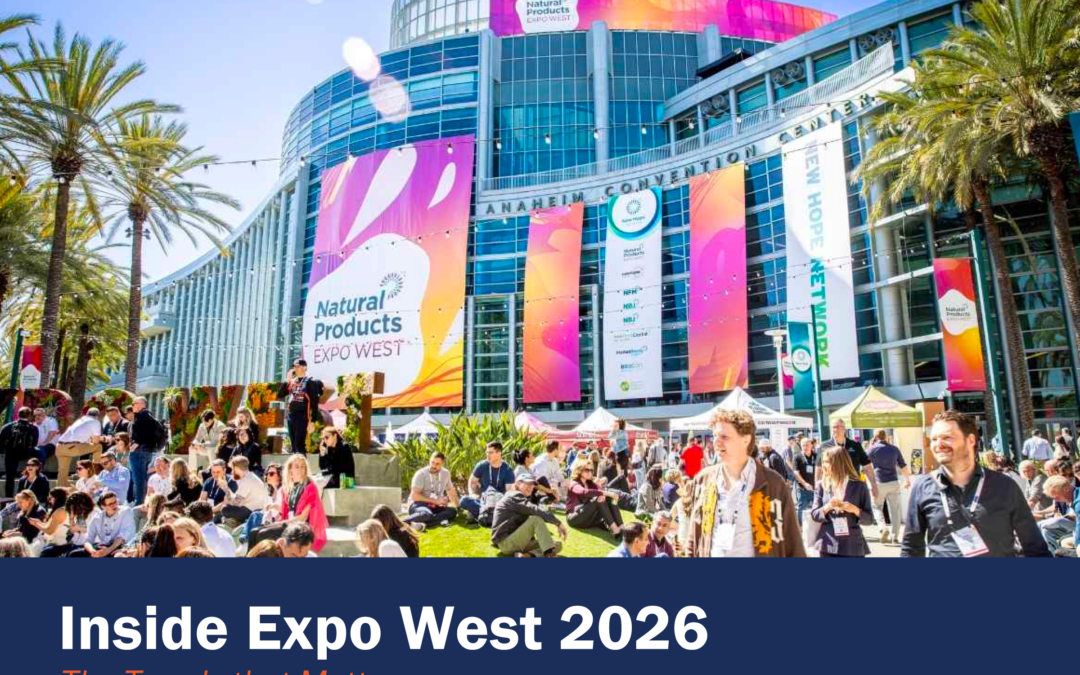
Each spring, Anaheim becomes the center of the CPG universe. Founders arrive with their passionate ideas, buyers hunt for the next breakout brand, and thousands of industry obsessives descend on Expo West to taste, debate, and trend-spot their way through the future of CPG. Team Seurat joined the fray once again this year—zig-zagging the halls of Expo West 2026 to scout the signals shaping the next wave of CPG. 

Of course, no Expo is complete without the unofficial currency of the show – the swag bags. This year’s contenders generated almost as much buzz as the products themselves, from Goyard-inspired totes to puffy Muscle Milk bags and Goodles collectible “Brand BFF” charm bracelets (yes, we proudly collected them all).

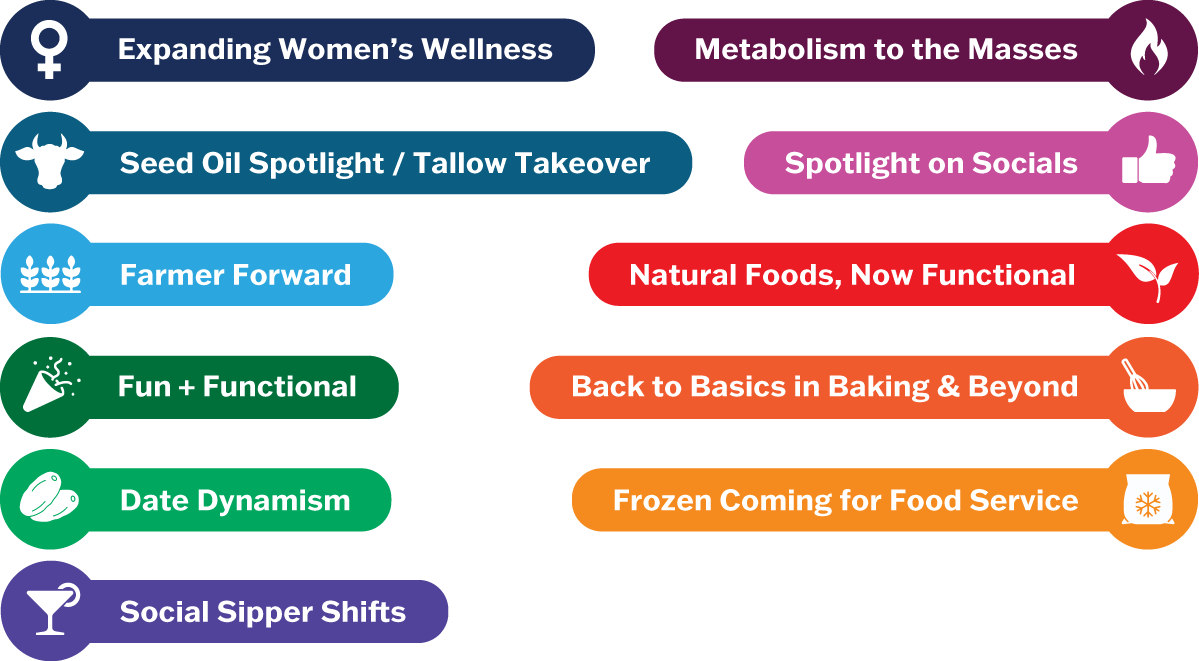
But beyond the tote bags and taste tests, Expo West remains the prime spot to take the pulse of where CPG is heading next. Many of the trends we identified last year are still going strong. The long-running protein parade marches on, taking on new and ever more creative forms. The Asian Frozen Feast has expanded into a broader frozen-versus-foodservice battle. And the “non-alc” space continues to evolve alongside shifting social rituals, building on the Mocktail Mojo we spotted. Several emerging themes have also clearly stepped into the spotlight — from the Great Animal Revival to Even Energy to what we’ve affectionately dubbed Honey, It’s Date Night. While we typically keep our roundup to a tidy top 10, this year Expo was extra – and so are we. So 11 trends it is. Here’s what we’re watching…

Expanding Women’s Wellness

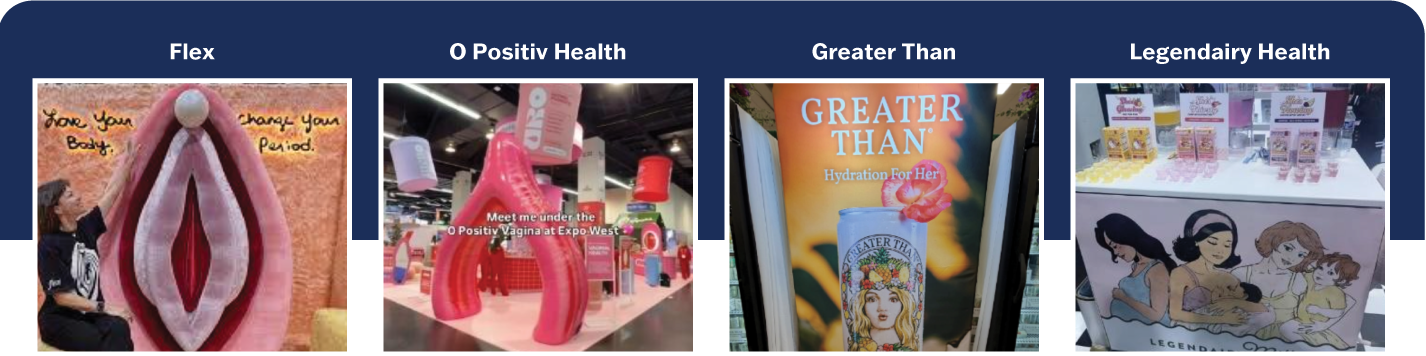
Women’s wellness wasn’t hiding at Expo West this year—it was on full display. From larger-than-life displays to boldly branded booths, women’s bodies and health needs were made overtly visible in a way that pushed stigma to the sidelines. The category no longer feels interested in whispering; instead, it is showing up with more confidence, candor, and cultural presence.

What felt especially notable was how far the conversation extended beyond period care. We saw solutions spanning adjustable menstrual discs, sexual wellness, and support for women across cycles and life stages—from pregnancy and breastfeeding to concerns like “mommy brain,” menopause, feminine balance, and hydration tailored to women’s needs. As awareness grows around the fact that women’s bodies have distinct needs—and that many of those needs have long been overlooked in a male-default world—brands across categories are beginning to respond more directly. What was once sidelined or simplified is increasingly being treated with greater specificity, nuance, and legitimacy.

Seed Oil Spotlight / Tallow Takeover

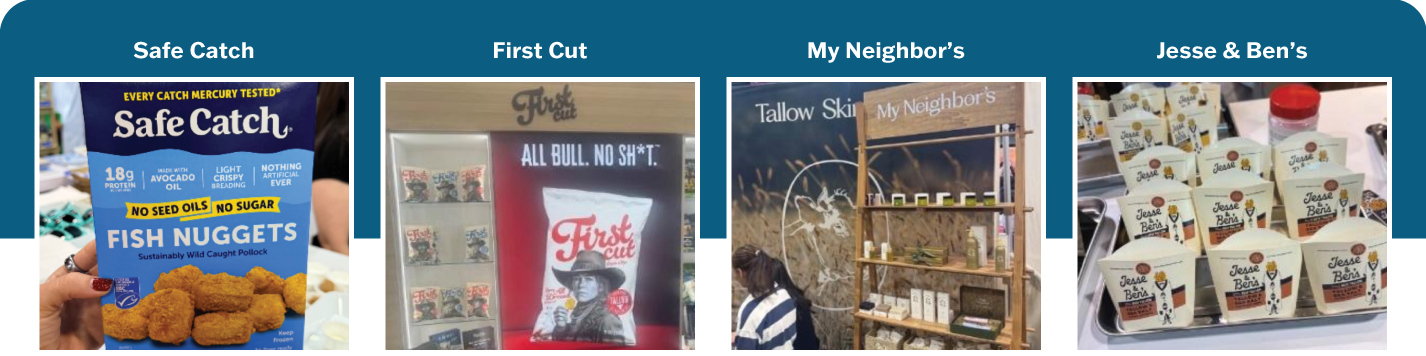
You almost could have played punch buggy with “no seed oils” claims at Expo West this year. Across food and beverage, the callout was everywhere—showing up on everything from bars and chips to coffee creamers, and starting to feel like one of the defining badges of the show floor. More than just an ingredient claim, “no seed oils” often functioned as shorthand for cleaner, more trustworthy formulation.

At the same time, tallow was turning up in places that would have felt surprising not long ago, from chips to skincare, signaling a broader return to traditional fats. Beneath the headline-worthy claims is a bigger shift in how consumers are thinking about fat itself. As skepticism grows around industrial food systems and highly processed ingredients, more brands are tapping into the idea that older, more familiar fats may feel more natural, wholesome, and trustworthy. What once seemed like settled nutritional wisdom is now back on the table, with consumers reexamining which fats they want in their food—and even on their skin.

Tallow: 

No Seed Oils: 

Farmer Forward

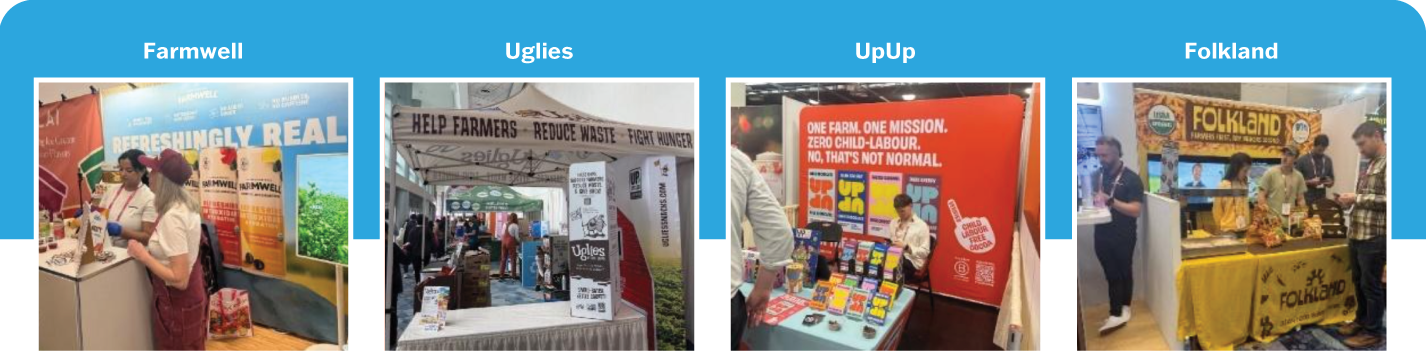
One word seemed to show up everywhere at Expo West this year: farmer. From booth signage to packaging to brand storytelling, brands leaned heavily into the people and places behind their products— highlighting farmer ownership, generational farms, regional sourcing, and closer connections between growers and consumers. Across categories, the emphasis was not just on what the product was, but on who grew it, where it came from, and the land it came from.

Connection to food is increasingly being built through stories of origin, the people who grow it, and the land it comes from. In a landscape where modern food systems can feel abstract and far removed, these cues help make products feel more grounded, transparent, and trustworthy. The result is a subtle but meaningful shift—from anonymous ingredients to food that feels rooted in real people and real places.

Fun & Functional

For years, functional health lived mostly in the world of VMS—clinical language, supplement bottles, and benefit-heavy messaging defining how consumers accessed wellness benefits. Over time, beverages helped bring functionality into more everyday routines. But Expo West suggested the next chapter may already be underway: functionality escaping both capsules and drinks to show up in entirely new formats.

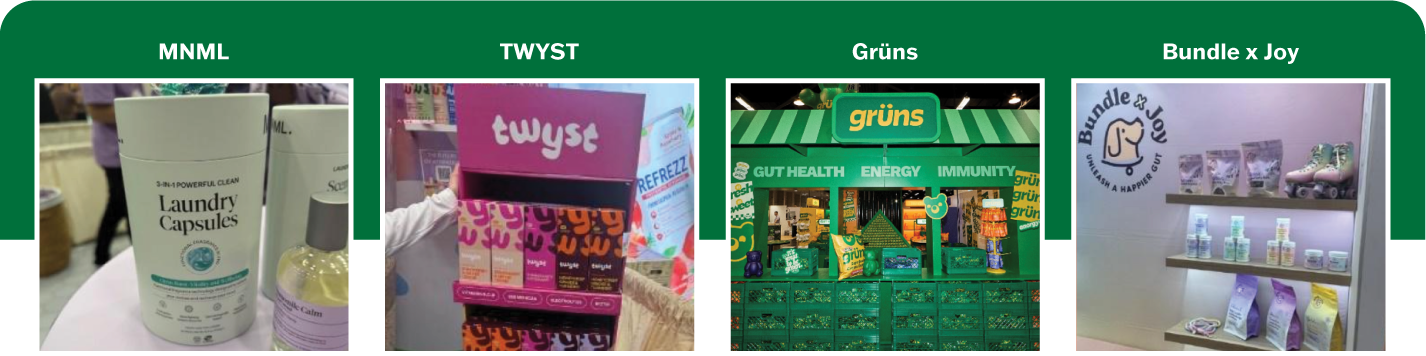
Across the show floor, benefits like energy, focus, gut health, glow, and relaxation were showing up in formats designed to spark curiosity and trial—from gummies, laundry capsules, pouches, gums, superfood spreads, skincare, wellness straws, and pet products. As the functional marketplace becomes increasingly crowded, brands are experimenting with formats that make wellness feel less clinical and more playful. Instead of asking consumers to adopt a strict regimen, these products weave functionality into everyday moments—inviting people to experience health benefits in ways that feel more surprising, accessible, and fun.

Date Dynamism

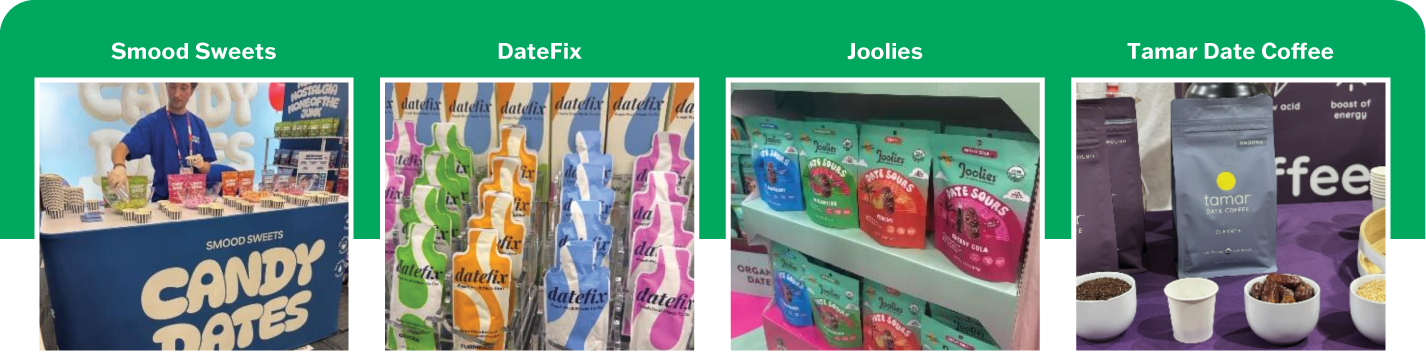
Dates are having a moment—and this year they were everywhere. While we spotted early signals of this trend last year, Expo West 2026 made it clear that dates are moving into the spotlight. Across the show floor, they showed up in formats ranging from snack bars and chocolates to syrups, spreads, and beverages, signaling that the ingredient is quickly expanding beyond its traditional associations. More than just a fruit, dates are increasingly being used as a way to deliver sweetness, texture, and substance across categories.

Their rise is also tied to a broader sweetener identity crisis. As consumers grow more skeptical of refined sugar, artificial sweeteners, and newer alternatives that can feel overly engineered, brands are actively debating what sources of sweetness feel most natural, trustworthy, and nutritionally meaningful. In that conversation, dates stood out as a clear frontrunner. They bring natural sweetness alongside fiber and other nutrients while offering something many sweeteners do not—satiety and a lower glycemic index through the combination of fructose & glucose. In a landscape full of sweetener confusion, dates are emerging as an ingredient that helps products feel both indulgent and wholesome.

Social Sipper Shifts

The sober-curious movement isn’t slowing down—but the category built around it is evolving. For years, alcohol-free beverages largely positioned themselves as substitutes for traditional alcohol, often centering on mimicry and replacement. But Expo West suggested the space is starting to move beyond that frame. Across the show floor, beverages were increasingly positioned around the feeling they create—whether that be calm, relaxation, uplift, focus, or a more social kind of buzz.

That shift points to a bigger change in what these drinks are being asked to do. Rather than simply standing in for alcohol, they are helping create entirely new rituals around how people unwind, connect, and socialize. For many younger consumers, alcohol is not necessarily something they are trying to replace—it is simply less central to their lifestyle to begin with. As a result, the opportunity is expanding from alcohol removal to mood creation—with brands designing beverages for the vibe, not just the void.

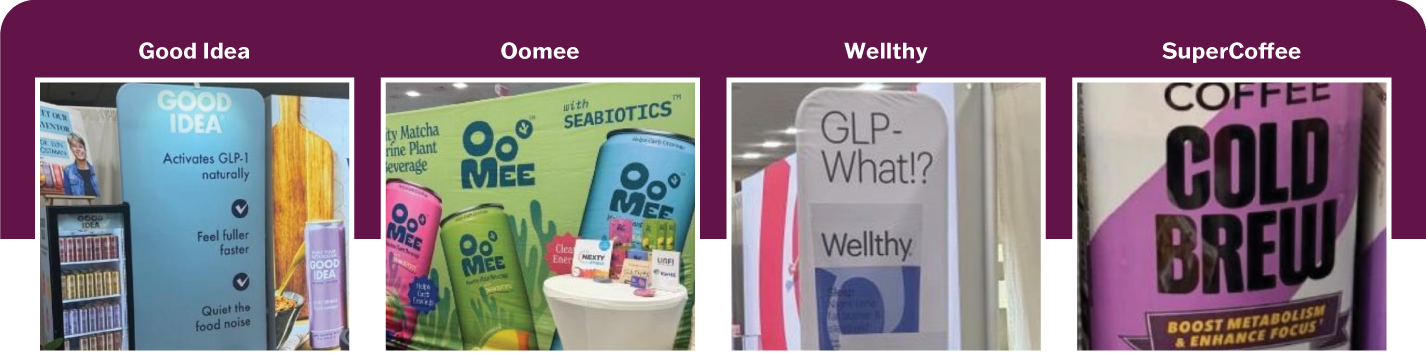
Metabolism to the Masses

For years, metabolism mostly lived in the worlds of clinical nutrition, fitness culture, and wellness diehards. Not anymore. Thanks in large part to the rise of GLP-1 medications, metabolism has entered the mainstream in a whole new way—bringing concepts like blood sugar balance, satiety, gut health, and metabolic efficiency into everyday consumer conversation. Expo West made it clear that brands are moving quickly to meet that shift, whether by speaking directly to GLP-1 users or by tapping into the broader outcomes people increasingly want: fullness, steadier energy, better blood sugar balance, and more support for weight management.

What stood out most was how quickly metabolism is becoming part of the vernacular. As consumers get more familiar with the mechanisms behind hunger, fullness, and weight, metabolism is starting to feel less like a niche health concept and more like everyday wellness shorthand. People are not just chasing weight loss—they are getting smarter about the system behind it.

Spotlight on Socials

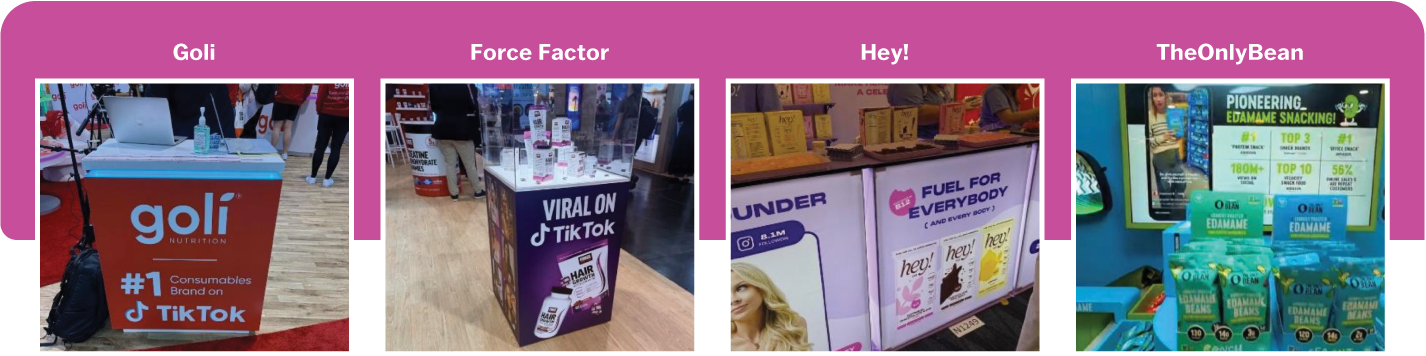
Scroll, like, buy, repeat. Social commerce has officially entered its main character era. Across Expo West, TikTok Shop, creator-led commerce, and social buzz came up again and again as powerful engines of discovery and demand generation. But more than that, social traction increasingly seemed to function as a kind of proof point—evidence that a brand has relevance, resonance, and real consumer pull. Booths proudly called out viral moments, creator momentum, and online success as signals that the brand was already winning with consumers.

That shift showed up across the show floor. Booths were designed to be filmed, shared, and talked about, with interactive activations and visually punchy moments built for content. Celebrity-backed brands added another layer of buzz, using star power to drive awareness and amplify talk value. Altogether, the message was hard to miss: in today’s landscape, success is not just measured by distribution—it is measured by attention. Social credibility is increasingly becoming both a reason to believe in a brand and a leading indicator of who earns the next shelf set.

Natural Foods, Now Functional

For years, Expo West innovation largely meant adding something extra—adaptogens, probiotics, collagen, or another functional boost layered onto foods and beverages. This year, the energy felt different. Instead of only fortifying products from the outside in, brands were increasingly unlocking functionality from the inside out—either by reengineering familiar foods to do more or by spotlighting the benefits already inherent in natural ingredients.

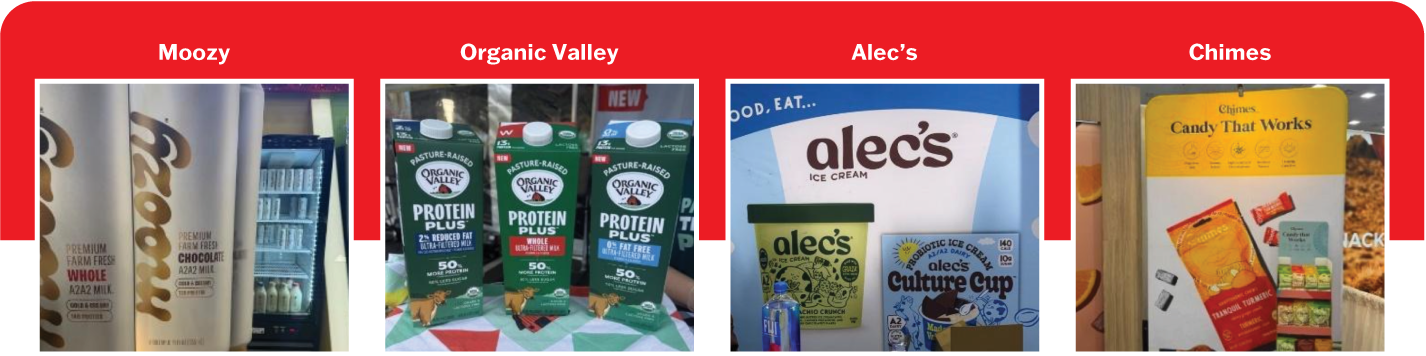
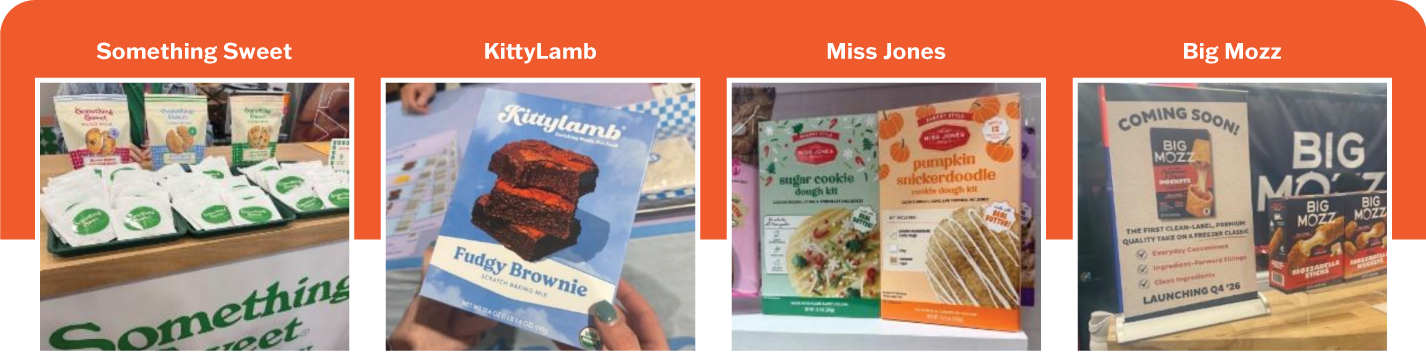
Dairy was one of the clearest examples of the first path. Once limited by a more traditional understanding of what milk could be, the category is being modernized through things like A2 proteins, ultrafiltration, and improved digestibility—expanding milk’s functional potential for today’s consumer. At the same time, other brands were leaning into the naturally occurring benefits of ingredients themselves, highlighting the specific compounds and properties found in foods like tomatoes, tart cherries, and ginger. Together, these approaches point to a broader shift: in a world increasingly skeptical of ultra-processed foods, functionality feels most compelling when it comes from real foods—or from a smarter understanding of what those foods can already do.

Back to Basics in Baking & Beyond

Expo West has long been a playground for reinvention. For years, brands looking to “upgrade” categories often did so by adding functional benefits or reworking familiar foods through alternative ingredients. That innovation was still present this year—but the pendulum also seemed to swing in a different direction: back toward real, simple, delicious food.

That shift showed up most clearly in baking, but it extended into other indulgent categories too. Whether in sweets, pizza, or comfort-food classics, brands seemed less interested in reinventing the original and more interested in restoring what made it lovable to begin with. Across categories, the emphasis was on cleaner ingredient decks, more premium formulations, and foods that felt more homemade, artisanal, and true to the enjoyment of the original. More than anything, these brands seemed focused on closing the gap that has so often existed between “better-for-you” and genuinely delicious—proving that high-quality ingredients and real enjoyment do not have to be at odds.

Frozen Coming for Foodservice

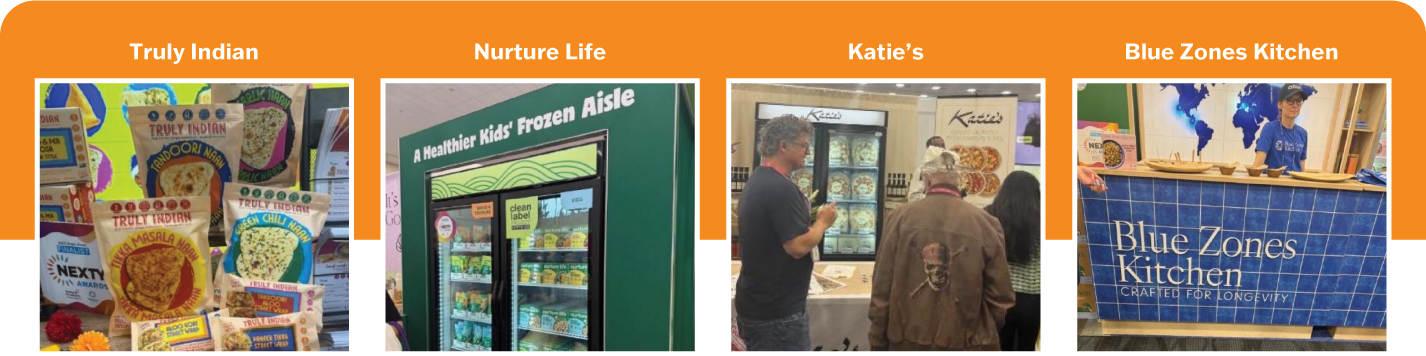
Boy, has the frozen aisle leveled up. A new generation of brands is working to reintroduce consumers to frozen by delivering the kind of quality, culinary credibility, and ingredient integrity that many may not associate with the set. Across Expo West, frozen products showcased globally inspired meals, chef-driven recipes, and cleaner ingredient decks designed to rival the quality and excitement consumers increasingly expect from foodservice.

That shift was especially visible in globally inspired cuisine, where frozen brands brought more authenticity, culinary specificity, and restaurant-like appeal to the aisle. Whether through dumplings, noodles, curries, or grain bowls, frozen brands seemed less interested in acting like pantry staples and more interested in acting like your favorite takeout spot. For consumers who may have written off the freezer years ago, these brands are making a case to come back—offering the convenience of frozen without the compromise once associated with it. As restaurant prices climb and convenience remains non-negotiable, brands that can deliver authentic, foodservice-quality experiences from the freezer are well positioned to win. The result is a growing standoff between restaurants and the frozen aisle—and frozen is coming in hot.

Expo West is where early signals start to look like real momentum. This year’s show made clear that consumers are seeking products that feel more real, more purposeful, more delicious, and in step with how they want to live.

Curious how your business can get in on these and future trends before they gain momentum at Expo West? As always, we welcome conversation at info@seuratgroup.com.

Challenger Brand Study 2026

Challenger Brand Study 2026

Challenger Brand Study 2026

Challengers who modernize and redefine their categories

Challenger brands are lauded for their disruptive values and their outsized contribution to CPG growth. While many “challenger” brands often play on the fringes, true breakthrough comes from going beyond niche disruption to redefining and modernizing existing categories.

This year’s study focuses on the next wave of challenger brands that are reigniting both consumer relevance and growth within their categories, not just for themselves.

Against a backdrop of stagnating unit growth and rising anti-consumerist sentiment, these brands demonstrate how to drive durable category value creation. They’re infusing new energy and modernity into sleepier categories by leaning into better-for-you ingredients, unlocking new consumption occasions, and leveraging lifestyle-driven branding to deepen consumer connection. In doing so, they’re pulling their categories back into the cultural zeitgeist and bringing new consumers into the fold.

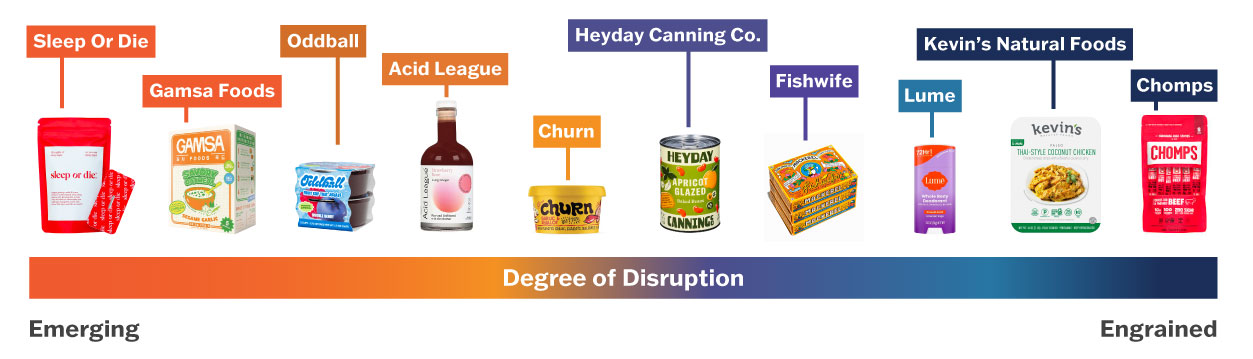
We are excited to highlight 10 challenger brands across a spectrum of disruption: from emerging challengers pushing boundaries to more established modernizers that have already reshaped consumer expectations.

What stands out across these brands is not a single playbook, but a shared orientation in designing for the future of the category, not fenced in by its present.

Challenger Brand Category Impact Spectrum

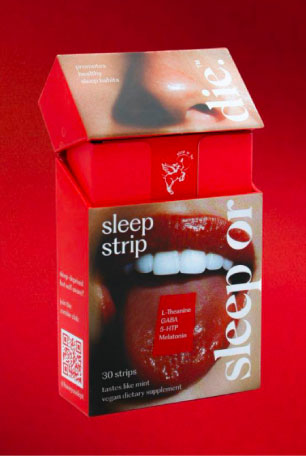
Sleep or Die: Sleep or Die is jolting the sleep aid category awake with provocative energy and functional credibility in a space that long felt clinical, lifeless, and, well, sleepy. Recognizing that millennials and Gen Z are desperately seeking rest but rejecting the sedative-heavy, side-effect-laden solutions of the past, the brand taps into a cultural shift where younger consumers are embracing wellness rituals but still crave the bold aesthetics of nightlife culture. By pairing credible functional ingredients like melatonin, L-theanine, and GABA with irreverence and design that feels more like a nightlife brand than a pharmacy product, then delivering it in a tab format that feels edgy and unexpected, Sleep or Die transforms the nightly wind-down into something bold and intentional. Sleep or Die is not just refreshing the sleep aid category. It is turning the nightly wind-down into something bold and current, not tired and medicinal. (Source 1 | Source 2 | Source 3) 

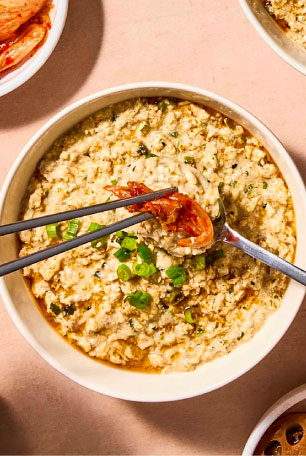
Gamsa Foods: Oatmeal is widely viewed as a healthy breakfast staple, but most bowls rely on sugary add-ons to make them appealing, leaving a gap for tasty, convenient, and savory breakfast options. Gamsa Foods recognized an opportunity to modernize without asking consumers to abandon familiar morning habits, introducing savory oatmeal inspired by traditional Korean porridge. Each bowl blends oats with quinoa and rice, layered with bold, umami-forward flavors like sesame, garlic, miso, and seaweed, delivering the warmth and comfort of a home-cooked Korean breakfast in a format ready in minutes. By infusing oatmeal with global flavor and cultural relevance, Gamsa reopens the breakfast category to savory, culturally grounded eating in a space long dominated by sweetness and sameness. (Source 1 | Source 2)

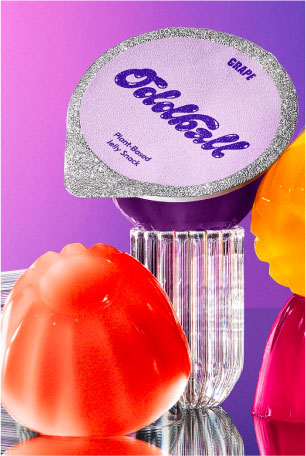
Oddball: Gelatin snacks have long been defined by a single legacy player, beloved for nostalgia but increasingly misaligned with modern expectations around ingredients and wellness. Oddball identified why consumers were quietly walking away. It was not because they stopped loving the jiggly, playful format, but because it no longer felt worth the compromise. By rebuilding jelly snacks with real fruit, plant-based gelling agents, and cleaner ingredients, Oddball gives consumers permission to enjoy a familiar childhood ritual without the artificial baggage. In a world where indulgence increasingly needs permission, Oddball offers a way to keep the fun without the guilt. With growing retail distribution and seed funding fueling expansion, the brand shows how even the most entrenched nostalgia-driven categories can be meaningfully modernized without losing their sense of joy. (Source 1 | Source 2 | Source 3 | Source 4)  

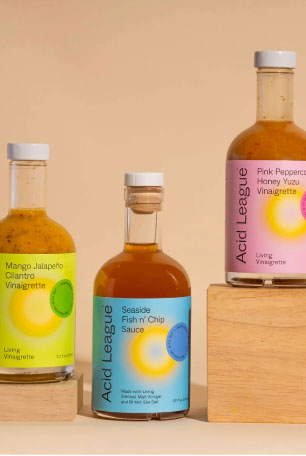
Acid League: The vinegar category has long suffered from low mindshare, treated as a commodity rather than an ingredient worth exploring. Acid League recognized that the category was quietly primed for a renaissance as interest grew in flavor complexity, functional benefits, and more creative uses for everyday pantry staples. By introducing premium, small-batch vinegars with bold, culinary-forward flavor profiles and design that feels curated, the brand repositioned vinegar as something to discover rather than simply stock. It turns vinegar from a dusty bottle in the back of the pantry into a flavor tool people actually want to reach for. As the category expands, Acid League sits squarely within a broader revival of this ancient functional food, unlocking new relevance and new usage occasions along the way. (Source)

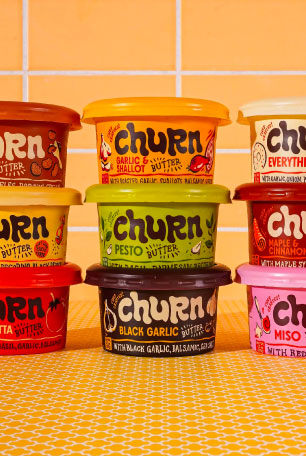
Churn: Founded by Chef Michael Tashman, Churn offers flavor-packed, wholesome butters designed to transform any dish into a bold, satisfying moment. From Parmesan and Pepper to the sweet warmth of Maple and Cinnamon, each tub is built to be a consumer’s sous chef, a simple tool that lets anyone confidently, conveniently, and affordably elevate their cooking. The brand wins by activating at the intersection of three emerging consumer trends: demand for convenience, flavor curiosity, and a preference for wholesome ingredients. In an era of burnout and economic uncertainty, Churn gives people a way to feel creative and capable in the kitchen again without more effort. In doing so, it helps turn a basic commodity into an accessible form of everyday indulgence. (Source)

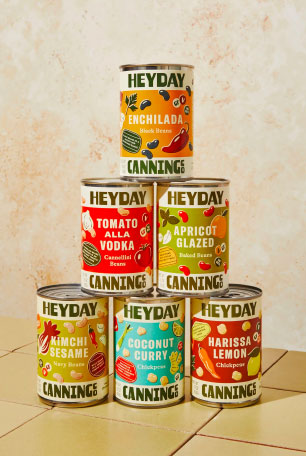
Heyday Canning Co.: Heyday taps into a simple tension: consumers love cans for their practicality, but the food inside has historically been uninspiring. The brand closes that gap by bringing creative flavor combinations and fresh-tasting, high-quality ingredients to a format people already trust. It delivers the cozy, nostalgic comfort of classic canned soups and pantry staples while pairing it with modern recipes and aesthetic packaging that feel genuinely exciting rather than like a compromise. As Heyday gains traction, including its recent launch at Target, it is helping the legacy canned food category evolve its relevance for today’s consumers. In doing so, Heyday is reintroducing an entire generation to canned food as something worth choosing, not just settling for. (Source)

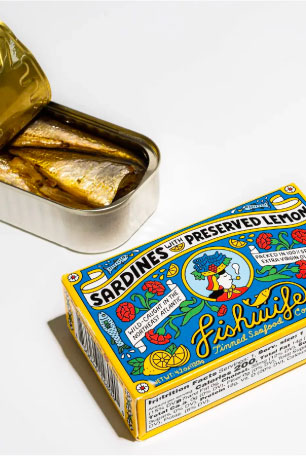
Fishwife: Fishwife is infusing bold flavor and fresh energy into a category that long felt bland and overlooked in the United States. Inspired by the high-flavor tinned fish culture of Spain, the brand taps into growing culinary curiosity and interest in globally inspired foods. By pairing sustainable, ethically sourced seafood with vibrant design and modern flavor profiles, Fishwife transforms tinned fish into an affordable, everyday luxury. The brand leans into charcuterie and “girl dinner” trends, delivering bites that are delicious, nutritious, and picture perfect. Fishwife is not just refreshing tinned fish. It is attracting entirely new consumers and redefining what canned seafood can represent in modern food culture. (Source 1 | Source 2 | Source 3)

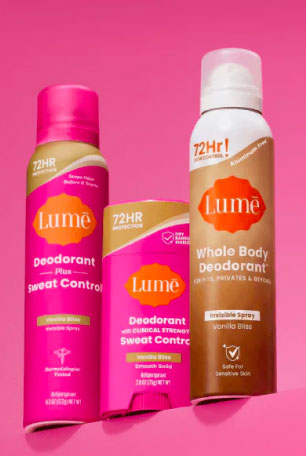
Lume: Born from OB-GYN Shannon Klingman’s experience with countless women raising concerns about body odor below the belt, Lume has reshaped expectations in deodorant by leading the charge on whole-body odor care. From traditional sticks and sprays to creams, cleansing washes, and wipes, Lume takes a different approach by acidifying the skin to block odor before it starts, using mandelic acid instead of aluminum or harsher, irritating ingredients. The brand also takes an unapologetic approach to education and destigmatization, openly talking about odor on social media in a way no one else in the category does. In doing so, Lume expands deodorant from a single-use product into a broader personal care category built around whole-body confidence. (Source)

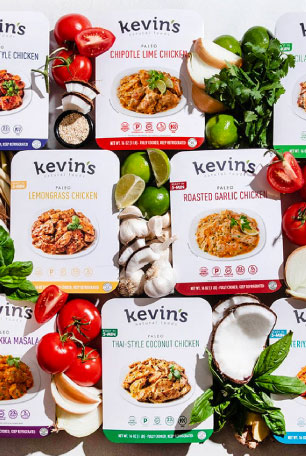
Kevin’s Natural Foods: Kevin’s did not just modernize frozen and refrigerated meals. It permanently changed what consumers and retailers expect from the category. Before Kevin’s, convenience meals were synonymous with compromise: heavy, artificial, and nutritionally suspect. Kevin’s proved that ready-to-heat could be clean, flavorful, and genuinely aspirational. Built on sous-vide preparation and real culinary flavors, the brand unlocked a new consumer truth: busy people no longer accept “good enough” food. Kevin’s explosive, unicorn-level growth forced retailers to re-architect the frozen aisle, making space for premium, chef-driven entrées and catalyzing the “fancy frozen” movement now sweeping the category. The brand’s 2023 acquisition by Mars is not just an exit story. It is evidence that Kevin’s successfully reset the economics and expectations of convenience food, pulling an entire category into a more premium, health-forward future. (Source 1 | Source 2) 

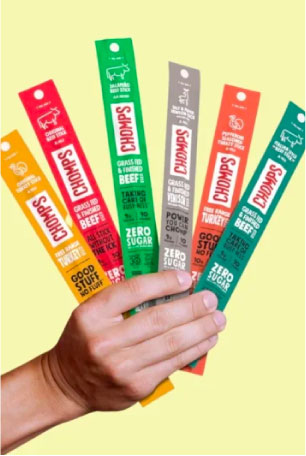
Chomps: Meat snacks carried baggage: perceived as over-processed, nutritionally suspect, and limited to a narrow consumer base. By rebuilding meat sticks with simple ingredients, clear quality credentials (100% grass-fed, Whole30-approved), and elevated packaging, Chomps made meat snacks feel modern, trustworthy, and approachable. The brand even leans into category stigma with self-aware messaging, “all the stick without the ick,” helping disarm skeptics and invite first-time users into the set. Chomps has already shifted the category’s center of gravity. Roughly two-thirds of its consumers were new to meat snacks before discovering the brand, helping establish clean-label protein as the new baseline for what meat snacks should be. Now one of the fastest-growing food brands in the U.S., Chomps is not just benefiting from category momentum. It helped create it. (Source 1 | Source 2)

Implications for All Brands

The challenger brands in this year’s study show how the challenger mindset has evolved. Across categories, these brands are actively reviving familiar categories and redefining what they stand for, and reimagining what they can become.

Even the most established categories can be reignited with the right insight and conviction. Because the strongest challengers do not just grow themselves, they help shape what comes next for the entire shelf.

As always, we would love to hear from you. If you would like more information on any of our challenger brand studies, or want to share a brand of your own, please reach out at info@seuratgroup.com.

Architecting Success

Architecting Success

Architecting Success

Brand architecture – the organizational system or structure underlying a portfolio – is something we don’t typically notice when it’s working well. The best examples go undetected: consumers naturally grasp a brand’s offering through carefully designed naming, color scheme, packaging, messaging hierarchy and organization of the physical or digital shelf. Like the bones of a house, we notice architecture only when it’s flawed – or worse, absent. Amid SKU proliferation, channel fragmentation & cluttered messaging, brand architecture can mean the difference between a product being selected or abandoned in a matter of seconds. This article unpacks brand architecture – when and why it works or doesn’t – with the goal of positioning it alongside other foundational tools in the brand management toolkit.

  • Companies managing multiple brands in the same category need to create clear “swim lanes” to ensure brands in the portfolio work together – not in competition – to capture a greater share of the pie. Especially in big CPG firms, companies often jump on a trend and leverage scale to deploy it broadly. Consider a pet company with multiple brands of dog food. Seeing the migration of “grain-free” from human to pet eating patterns, they might add a grain-free SKU to each of their brands. Without a clear portfolio architecture, lines between brands become blurred. Perceived differentiation declines, and along with it, willingness to pay.
  • Individual brands in growth mode find themselves in the (enviable) position of launching new products to reach incremental consumer segments, needs or occasions. Motivated by a desire to bring products to market quickly, these brands create new sublines, formats and/or varietals – but then encounter challenges when consumers are forced to discern differences between legacy and new products. Consider a juice manufacturer responding to consumers’ desire for less sugar and fewer calories. The creation of a new “Lite” subline to complement existing “Diet” products, while well-intentioned, may ultimately confuse shoppers who lack the time or patience to read nutrition panels.

Enter architecture, the art & science of organizing a collection of products or brands to drive clarity, distinctiveness & incrementality. Successful businesses use architecture to penetrate new consumers and/or need states, help shoppers quickly intuit differences across a portfolio and even create guardrails for innovation.

While there are numerous ways to organize a portfolio, most ladder up to one or more of the following:

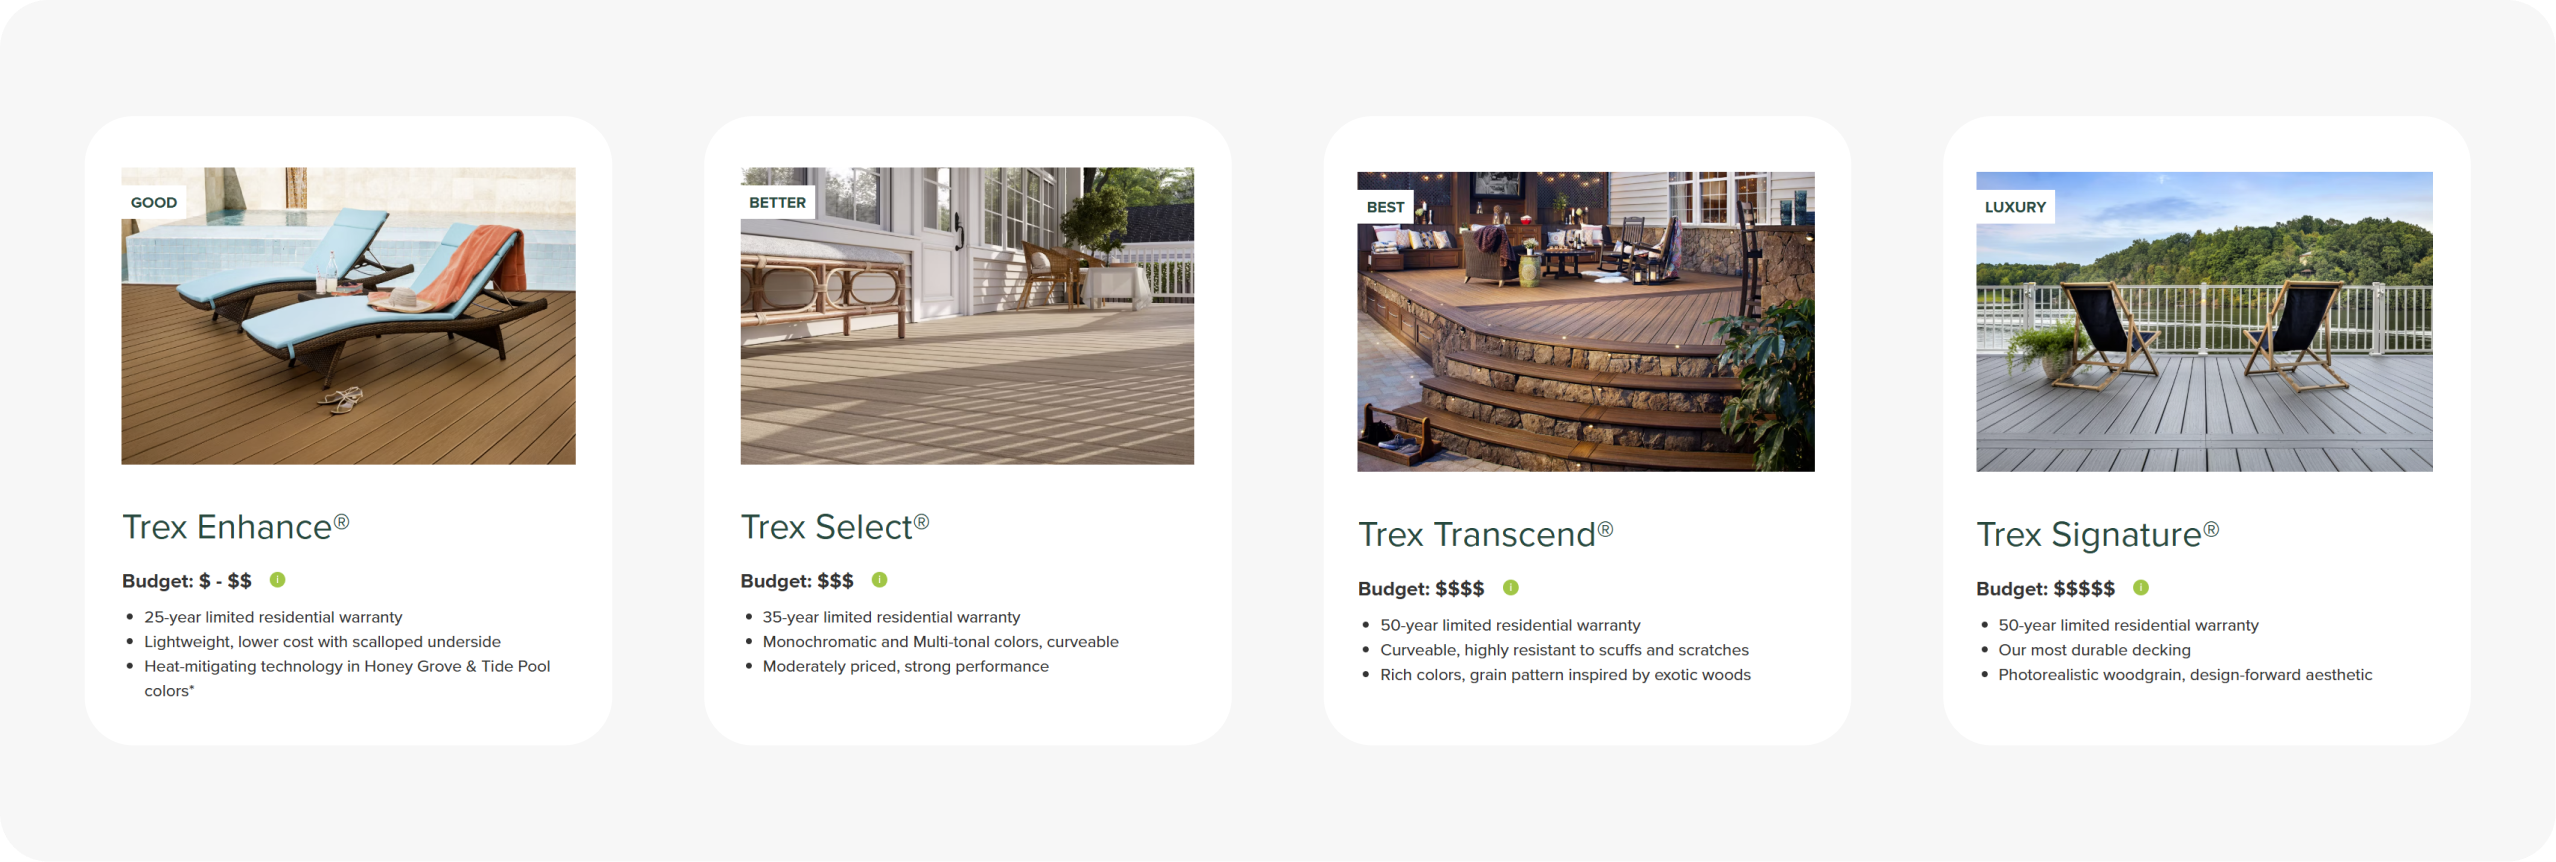
Brands organize portfolios based on price tier, often in the form of a good / better / best construct.

Example: Composite decking company Trex offers products in four tiers – Trex Enhance® (Good), Trex Select® (Better), Trex Transcend® (Best) and Trex Signature® (Luxury). Differences in warranty duration, available colors, heat resistance and durability justify price differences and help shoppers choose a product that matches their budget and definition of value.

Brands organize portfolios based on a highly discernible product attribute like flavor, ingredient type or format.

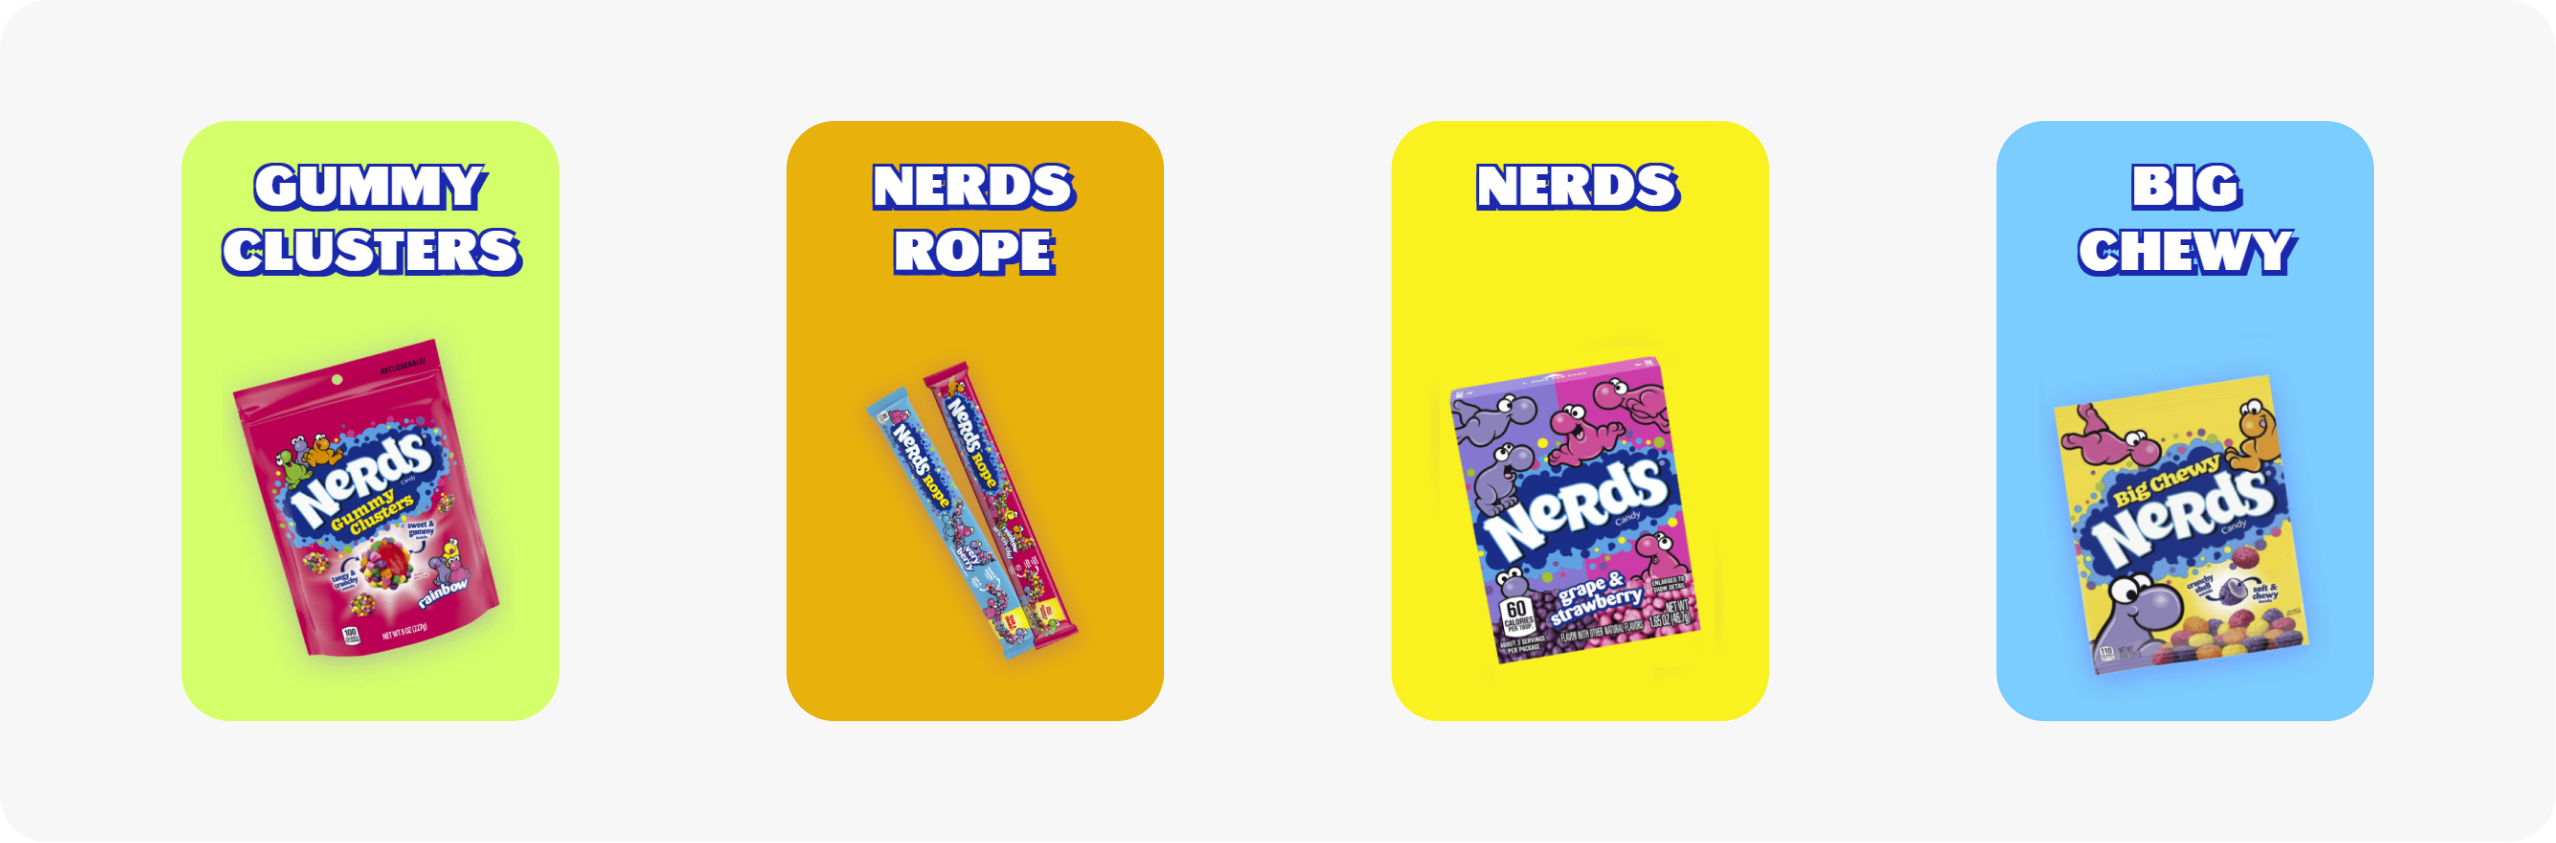
Example: Ferrara’s Nerds candy offers consumers four ways to enjoy: classic, rope, big chewy & gummy clusters. This architecture has myriad benefits, from courting consumers who typically buy other formats (e.g., gummy lovers) to justifying incremental shelf space and commanding a premium for novel experiences.

Brands organize portfolios based on the end users for whom the products are designed, often corresponding to specific markets or channels.

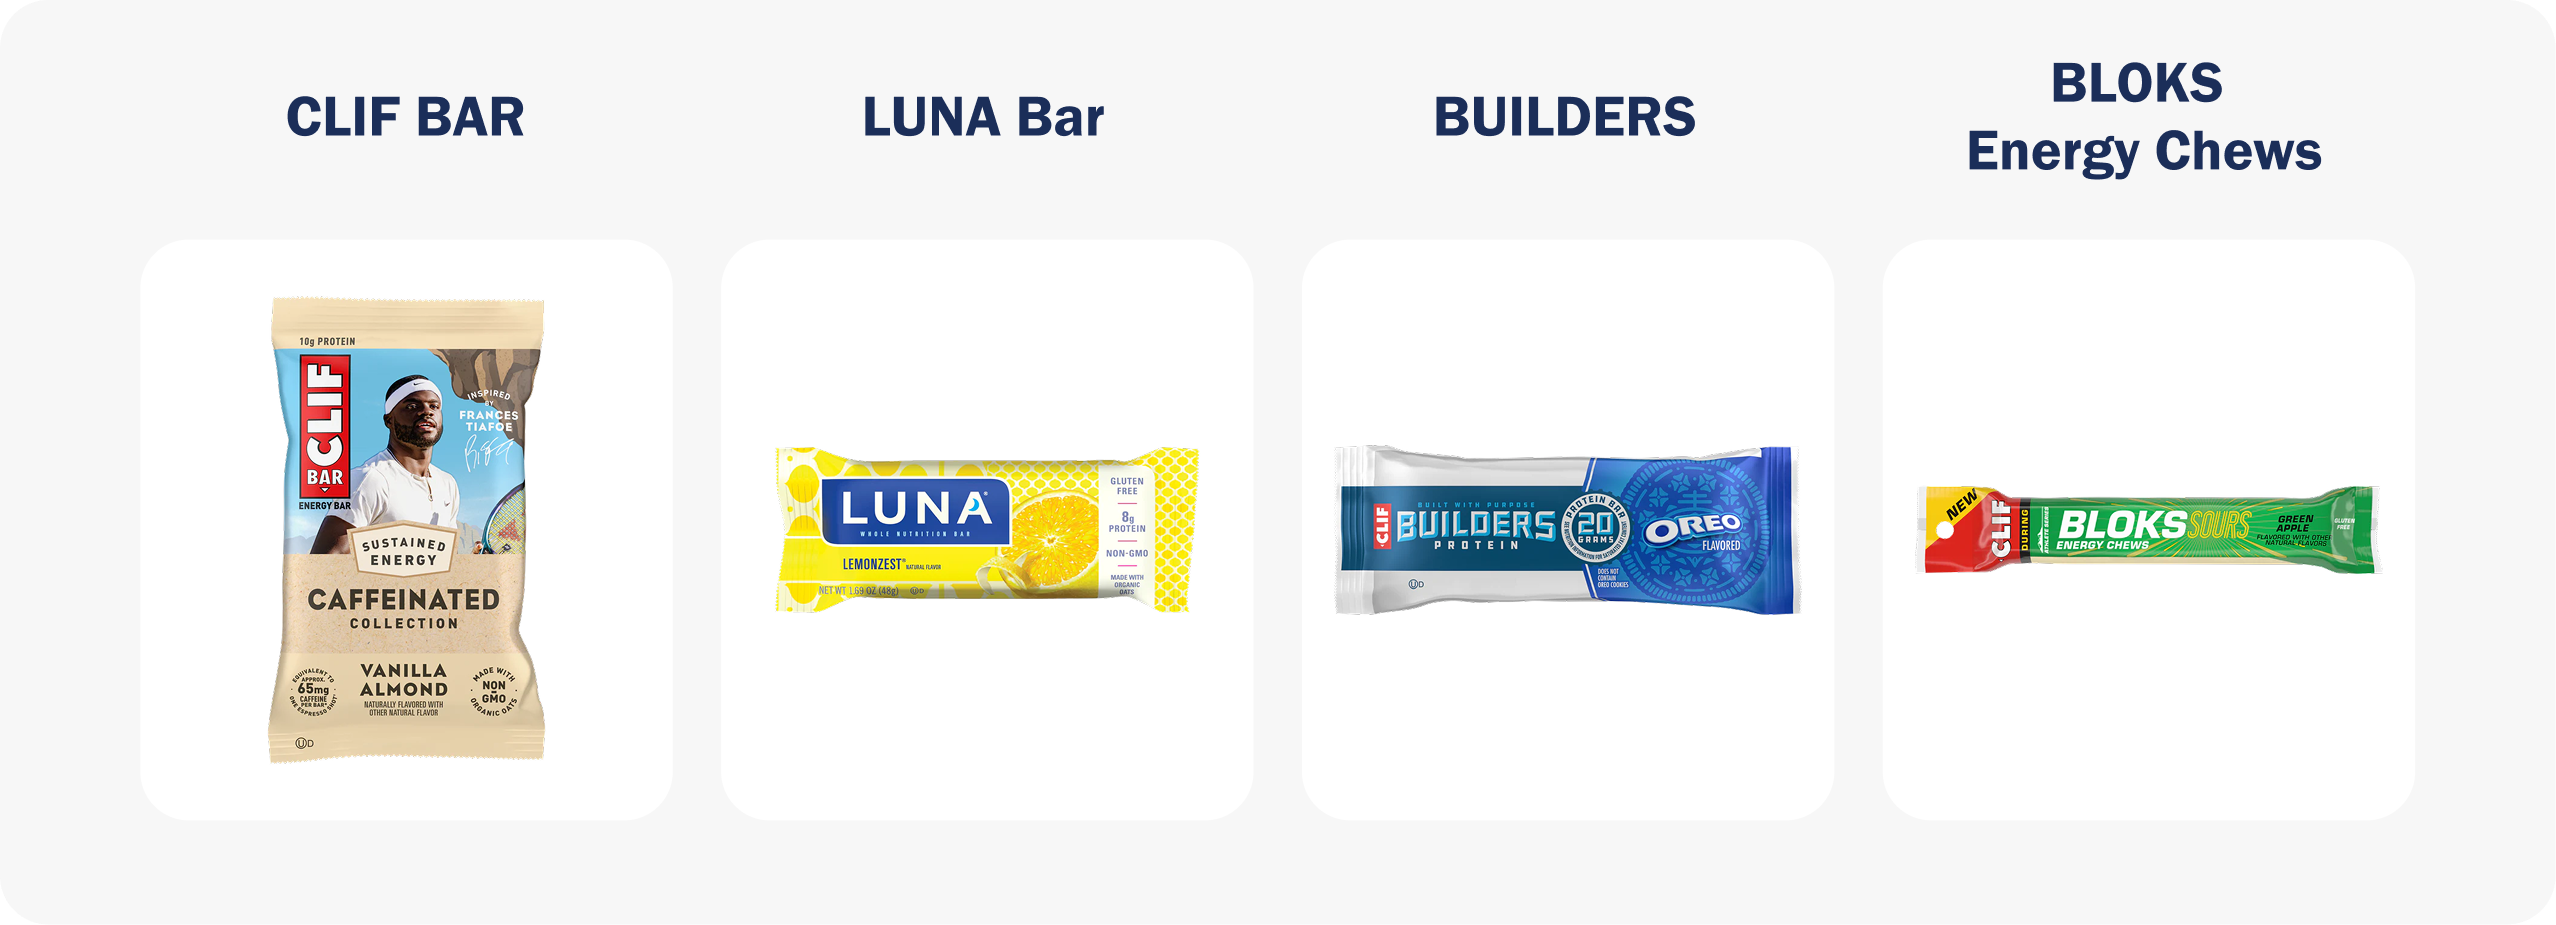
Example: CLIF bar offers products for kids (ZBAR), women (LUNA), protein-seekers (BUILDERS) and hardcore athletes (BLOKS). Through this structure, Mondelez can not only recruit new consumer segments to the franchise but also prioritize distribution in specific channels like sporting goods stores.

Brands organize portfolios based on what the product does for consumers.

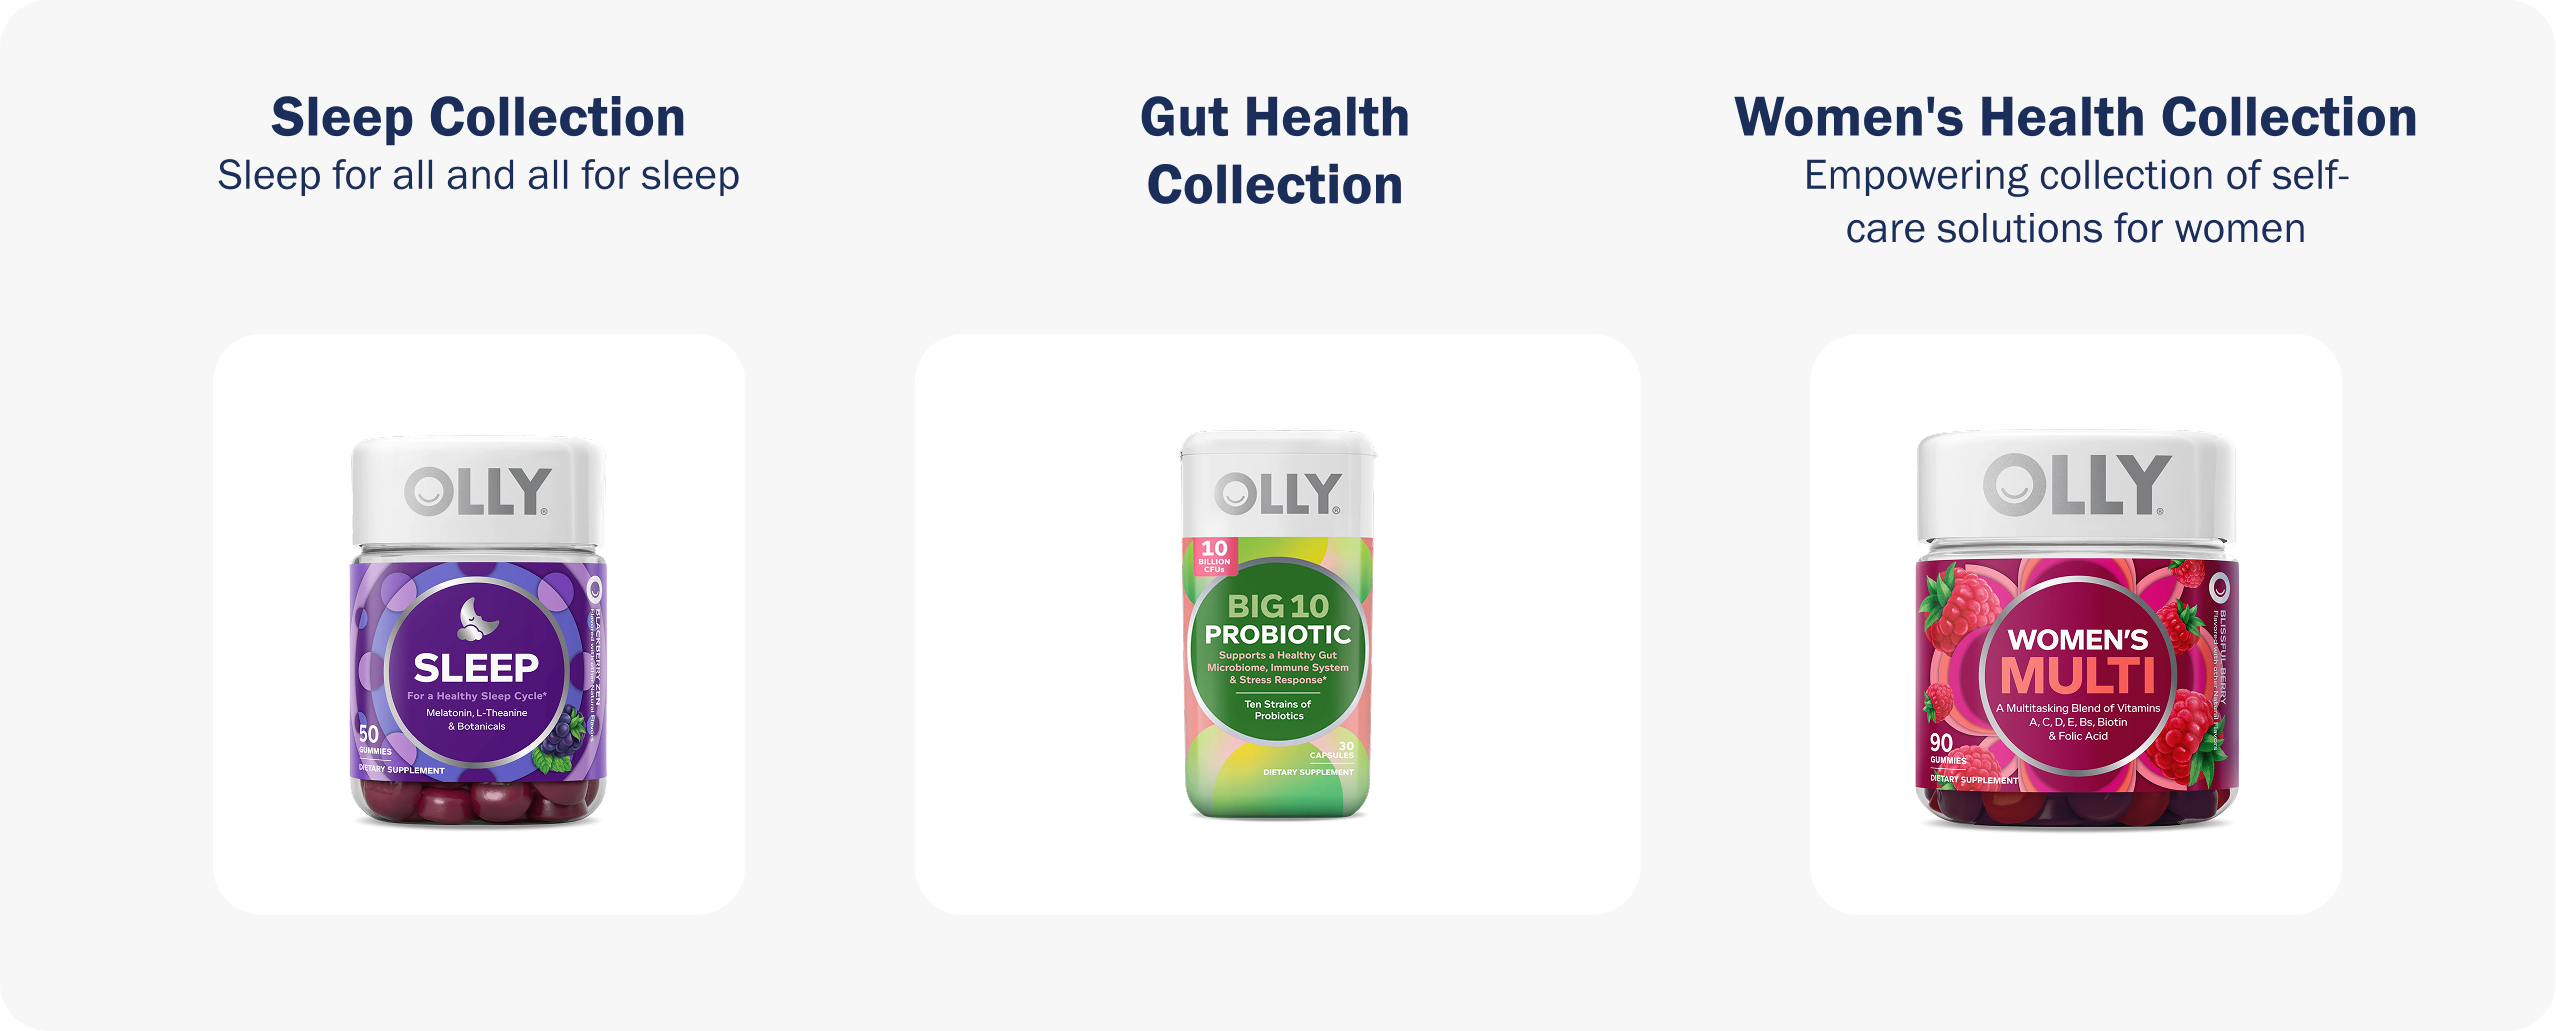
Example: OLLY famously pioneered benefit-led communication in the vitamins & supplements category. While the brand targets wellness-oriented women 25-44, its portfolio organized by sleep, mood, beauty, gut health, women’s health and immunity allows Unilever to effectively show up for VMS shoppers prioritizing these benefits while informing distinctive memory structures (sleep = purple, gut health = green).

In the case of newer categories that require more consumer education, like, say, nootropics, it’s often appropriate to organize based on one of the first two dimensions (i.e., what the product is). In our experience, however, some of the best brands organize their portfolios based on an amalgamation of these dimensions – effectively combining what it is with who it’s for and what it does.

The world’s largest hospitality company with 39 brands, Marriott understands architecture well. Take its flagship and namesake brand, which spans the select service, premium & luxury tiers. Each brand has a unique set of services and amenities, offered at varying nightly rates (what) inspired by distinct traveler profiles (who) and how they view the role of a hotel in travel (why) – united by the master brand’s core visual identity and brand promise.

  • Courtyard by Marriott is for value-conscious guests who want convenient, flexible, no-frills travel experiences
  • Marriott is for conservative travelers who find safety & security in familiar hospitality experiences from a well-known, trusted brand
  • JW Marriott is for premium guests who associate travel with wellbeing and seek elevated amenities & experiences that inspire

Everything about these sub-brands – from the 2D and 3D visual identities to the nightly rates, staff uniforms, check-in experience, onsite amenities and F&B programming – flows from this carefully orchestrated architecture.

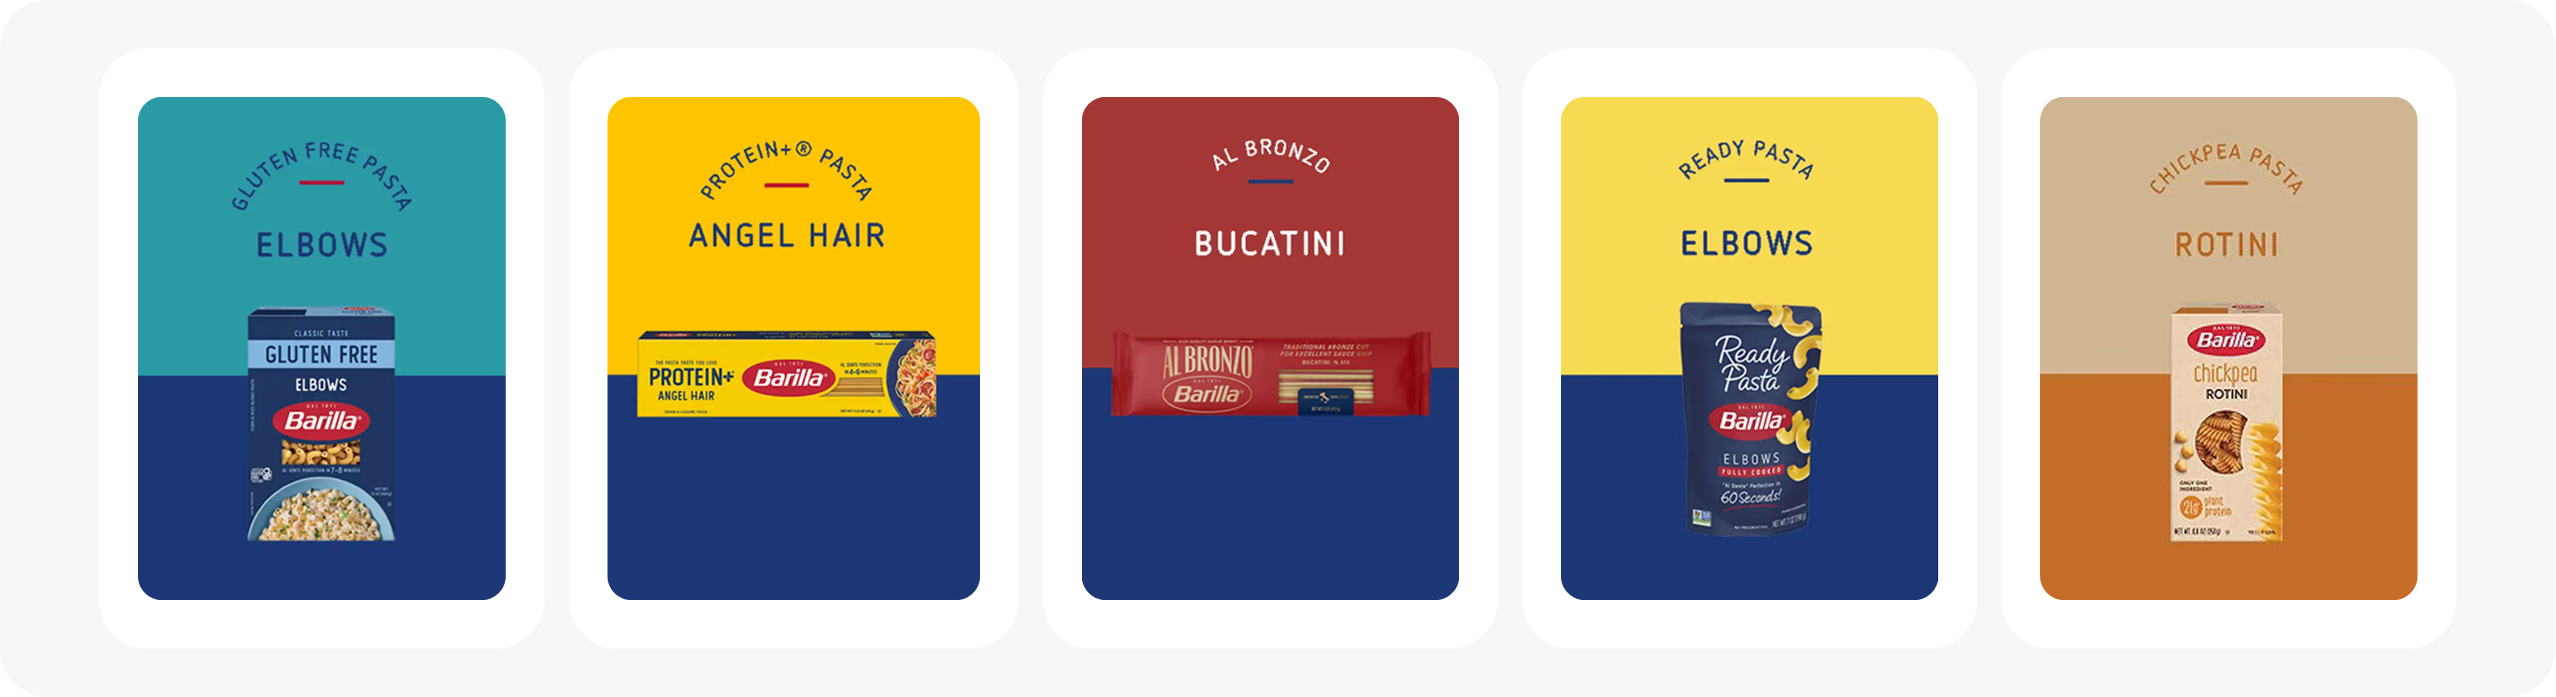
Having been around for almost 150 years, Barilla has learned a thing or two about architecture. While most of its U.S. volume is classic blue box, in recent years the brand has proliferated to reach different consumers with nuanced needs at varying price points.

  • Gluten-Free, Whole-Grain and Protein+ are for pasta lovers with dietary and/or macronutrient goals
  • Al Bronzo is for home chefs who want a premium taste experience without the fuss of homemade pasta
  • Chickpea & Red Lentil is for carb avoiders who prioritize nutrient density but don’t want to sacrifice their pasta ritual
  • Ready Pasta is for consumers short on space, time & cooking utensils who still want a home-cooked meal

Notably, Barilla uses product naming, color, packaging shape and messaging hierarchy to quickly and effectively resonate with each of these consumers and use cases.

The good news is, it’s never too late to create (or optimize) the system or structure underlying your brand. You don’t need a degree in architecture – just a strong brand identity, a deep understanding of how consumers engage with your category and a network of partners to bring it to life.

Interested in learning more? Contact us at info@seuratgroup.com.